Helping an Aging Parent With Banking: Convenience Accounts, Power of Attorney, and Joint Ownership Compared
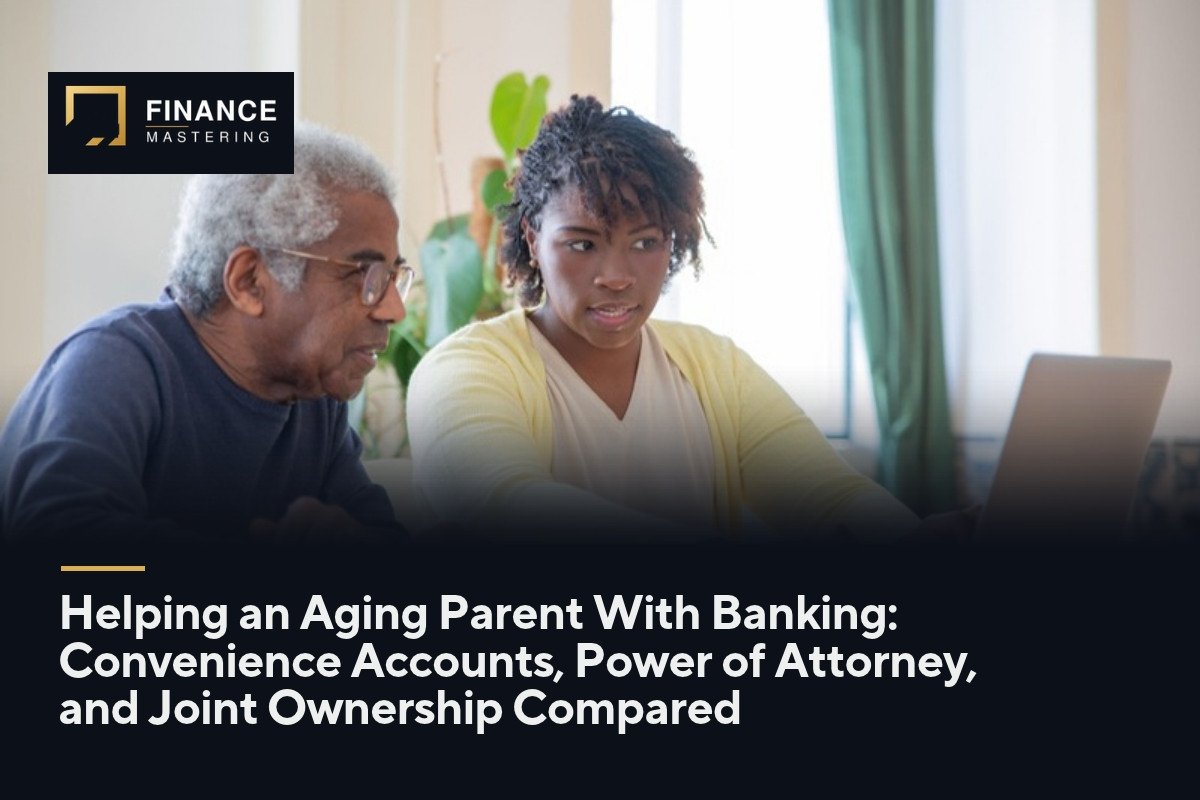
It often starts with something small. A missed utility payment. A stack of unopened bank statements on the kitchen table. A phone call from your mom asking whether a "bank investigator" really needs her account number. At some point, many adult children realize their parent needs help with money, and the next question is how to get access in a way that is safe, fair, and legal.
There is no single right tool. Banks and the law offer several options, and each one gives a different kind of authority, carries different risks, and has different consequences when your parent dies. This guide compares the most common options side by side so you can have an informed conversation with your parent, your siblings, and, ideally, an attorney.
This article is general information, not legal advice. Laws on powers of attorney, account ownership, and Medicaid vary by state, and a local elder law or estate planning attorney can tell you how the rules apply to your family.
First, Separate Three Questions
Before choosing a tool, it helps to pull apart three separate questions that often get blended together.
Who can pay bills and move money today? Who owns the money, legally, while your parent is alive? And who gets the money when your parent dies? A tool that answers the first question well can create problems with the second or third. Keeping those questions separate is the best way to avoid surprises later.
Option 1: Adding You as a Joint Owner
The most common move is also the riskiest. When you are added as a joint owner, often with right of survivorship, you generally become a co-owner of the money in the account. You can write checks, make withdrawals, and talk to the bank. When your parent dies, the account usually passes directly to you as the surviving owner, outside the will.
That convenience comes with real tradeoffs.
Creditor exposure. Because you are an owner, your own creditors may be able to reach the account in some situations, depending on state law. A lawsuit, a judgment, or a divorce on your side could put your parent's savings at risk.
Inheritance surprises. If your parent's will splits everything equally among three children but the main bank account is joint with only one of them, that account may pass entirely to the joint owner. Families sometimes assume the joint owner will share it, but the law may not require that.
Gift and tax questions. Adding someone to a bank account generally is not treated as a completed gift for federal gift tax purposes until the added owner withdraws money for their own benefit. If that happens, amounts over the annual gift tax exclusion, which is $19,000 per recipient in 2026, may require a gift tax return, though owing gift tax is uncommon.
Medicaid concerns. Medicaid long-term care programs review asset transfers made during a look-back period, which is generally 60 months. Money a joint owner takes out of a parent's account may be treated as a transfer, which can affect eligibility. The rules are complex and state-administered, so get advice before moving money if long-term care is possible.
If you do choose joint ownership, put your family's intentions in writing, and make sure the will and any beneficiary designations tell the same story. That will not override the account title, but it reduces confusion later.
Option 2: A Convenience Account or Authorized Signer
Some banks and some states offer a middle ground. A convenience account, sometimes called an agency account, or an authorized signer arrangement, lets you write checks and make deposits on your parent's behalf without becoming an owner. The money remains your parent's, and at death it generally passes according to the account's beneficiary designation or the estate, not to you as a co-owner.
This option addresses the first question, paying bills, without changing the second and third. The availability of these accounts, what they are called, and how they work vary by bank and by state, so ask your parent's bank what it offers. If the bank only offers joint ownership, ask specifically whether it can add a signer without ownership rights.
Option 3: A Durable Power of Attorney
A power of attorney is a legal document in which your parent, called the principal, names someone, called the agent, to act on their behalf. A durable power of attorney stays in effect if your parent later loses capacity. That durability is what makes it valuable for aging-related planning.
Under a financial power of attorney, you act as a fiduciary. The Consumer Financial Protection Bureau's guides for agents describe the core duties: act only in the person's best interest, manage their money and property carefully, keep their money separate from yours, and keep good records. You are not an owner, and the money does not become yours at death.
Your parent must have the mental capacity to sign a power of attorney, which is one reason to do it early. Banks may review the document before accepting it, and some ask that you use their own form. State laws on whether a bank must accept a valid power of attorney vary. Bringing the document to the bank well before it is needed avoids a frustrating standoff in a crisis.
A power of attorney ends when your parent dies. At that point, the executor named in the will, or an administrator appointed by a court, takes over.
Option 4: Payable-on-Death and Transfer-on-Death Designations
A payable-on-death designation, often called a POD, lets your parent name one or more beneficiaries on a bank account. A transfer-on-death designation, or TOD, does something similar for brokerage accounts. During your parent's life, the beneficiary has no access and no ownership. At death, the account passes directly to the named beneficiaries, generally without probate.
POD and TOD designations address the third question, who inherits, without creating the risks of joint ownership. Many families pair a POD designation naming all the children equally with a power of attorney for day-to-day help. That combination keeps ownership with the parent, gives a trusted person authority to act, and keeps the inheritance split as intended.
Option 5: A Trusted Contact on Investment Accounts
Brokerage firms are required to make reasonable efforts to ask customers for the name of a trusted contact person, under rules overseen by FINRA. The trusted contact must be at least 18. The firm may reach out to that person if it cannot reach your parent or suspects financial exploitation, and to confirm details such as your parent's health status or the identity of a legal guardian or agent.
A trusted contact cannot make trades, see account details as a matter of right, or move money. It is a safety net, not a form of access, and it costs nothing to set up. If your parent has brokerage or retirement accounts, adding a trusted contact is a low-risk first step.
Option 6: Representative Payee for Government Benefits
If your parent receives Social Security or Supplemental Security Income and cannot manage those payments, a power of attorney is not enough. The Social Security Administration says that being an authorized representative, having power of attorney, or sharing a joint bank account with the beneficiary is not the same as being a representative payee. Treasury does not recognize a power of attorney for negotiating federal payments.
To serve as payee, you apply through Social Security and must be appointed. A payee must use the benefits for the beneficiary's current needs, save the rest for their benefit, keep records, and report to Social Security when asked. The account must be titled so it is clear the money belongs to the beneficiary. The Department of Veterans Affairs has a similar fiduciary program for VA benefits.
A Comparison in Practice
Example: Gloria Ramirez, 82, lives in Tucson. Her daughter Ana lives nearby and handles most errands. Her son Luis lives in Chicago. Gloria's will leaves everything equally to both children.
If Gloria adds Ana as a joint owner on her checking and savings accounts, Ana can pay bills easily. But at Gloria's death, those accounts may pass entirely to Ana, regardless of the will. If Ana gets sued after a car accident, Gloria's savings could be pulled into it in some states.
If Gloria instead signs a durable power of attorney naming Ana, adds POD designations naming Ana and Luis equally, and names Luis as trusted contact on her brokerage account, Ana can manage bills, the money stays Gloria's, and both children inherit equally. Luis also gets a role that lets the brokerage firm reach him if something seems off.
The second setup takes more paperwork, but it lines up with what Gloria actually wants. That is the test to apply to any arrangement.
When Your Parent Cannot Sign Anything
If your parent has already lost capacity and has no power of attorney, the options narrow. A court-appointed guardian or conservator may be needed, which is generally slower, more expensive, and subject to court oversight. This is the strongest argument for setting up documents early, while your parent can make their own choices.
Questions to Ask Your Parent's Bank
A short call or branch visit can save weeks of back-and-forth later. Bring your parent if you can, since many banks will only make changes with the account owner present or on the phone.
Ask whether the bank offers a convenience or agency signer option, and what rights that person would have. Ask what the bank requires to accept a power of attorney, including whether it reviews outside documents and how long the review takes. Ask whether POD beneficiaries can be added online or require a form. Ask whether a second person can receive copies of statements or fraud alerts without becoming an owner.
Write down the answers, the date, and the name of the person you spoke with. Policies differ between banks, and even between branches, so it helps to have a record.
Keeping Siblings in the Loop
Money disputes between siblings often start with silence rather than bad intentions. If one child handles the finances, agreeing early on how and how often updates will be shared can prevent suspicion later. A simple monthly summary of bills paid and balances is usually enough.
Protecting Your Parent, and Yourself
Whatever you choose, document everything. Keep receipts, use separate accounts, and avoid mixing your money with your parent's. Share regular summaries with siblings if they are involved. These habits protect your parent from mistakes and protect you from accusations.
Watch for warning signs of scams aimed at older adults, such as sudden urgent requests for gift cards, wire transfers, or payment apps. Banks can help: ask whether they offer alerts on unusual activity or allow you to view statements as a power of attorney agent.
The Bottom Line
Start with a conversation, not a form, and ask your parent what they want to happen both now and later. Then bring that answer to a local attorney and the bank, and pick the tools that match it.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
James Johnson has 10+ years in fintech. He holds an MBA and an MS in Information Technology, and writes about how AI and personal finance actually meet for everyday investors.
Comments (0)