

Overdraft Protection: Helpful Safety Net or Expensive Trap?
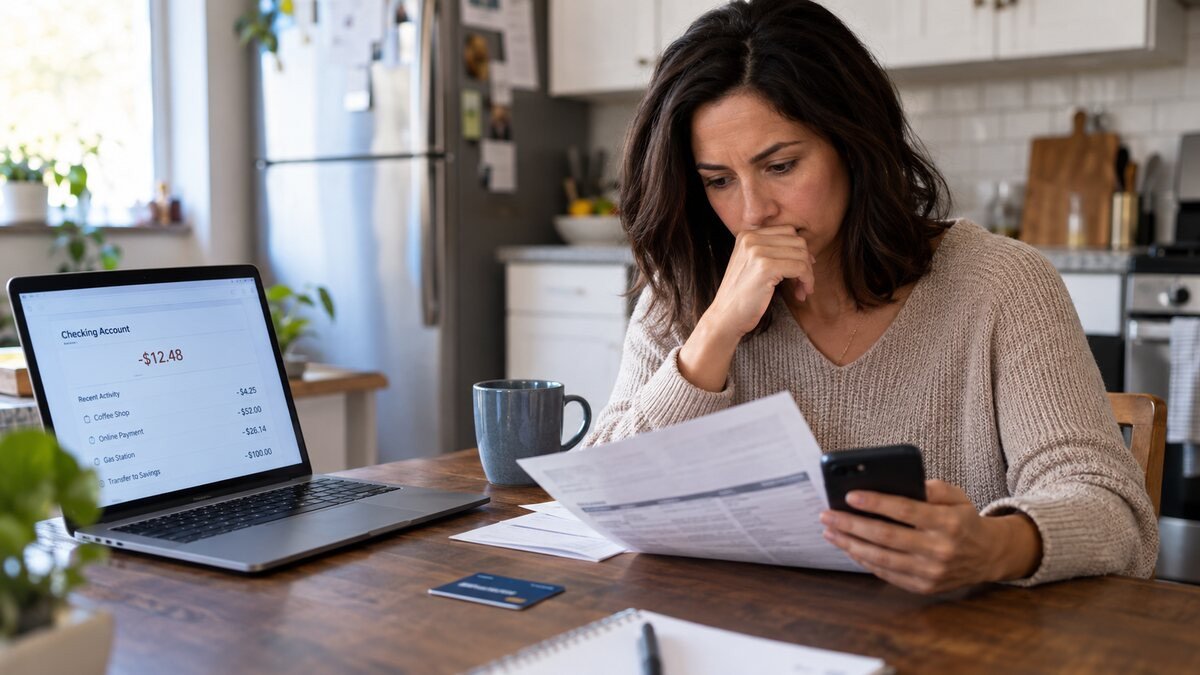
Overdraft protection sounds like a kindness: if a payment exceeds your checking balance, the bank covers it so the transaction goes through. For some people, that coverage prevents an embarrassing decline at the grocery store or a late utility fee. For others, it becomes a recurring bill that quietly costs more than the problem it solves.
Understanding the difference between helpful coverage and an expensive trap starts with definitions. Banks use several products under similar names, fee schedules change, and your own cash-flow habits determine whether the feature saves money or drains it. This guide explains how common overdraft tools work, what they cost in real life, safer alternatives, and how to decide with clear eyes rather than fear or marketing language.
What people usually mean by overdraft protection
There is no single product called overdraft protection. Consumers often blur three ideas together. First is standard overdraft coverage, where the bank pays a transaction that exceeds your balance and charges an overdraft fee. Second is overdraft transfer or linked-account protection, where the bank moves money from savings or a credit line to cover the shortfall, sometimes for a transfer fee. Third is courtesy coverage for everyday debit card and ATM transactions, which often requires your opt-in under consumer rules for many one-time debit card and ATM overdrafts.
Those distinctions matter because the fees, limits, and consumer rights differ. A linked savings transfer of twenty dollars with a small transfer fee is a different economic event from a thirty-five dollar overdraft fee charged multiple times in one day. Before you judge the feature, identify which version your bank offers and what you actually enrolled in.
Also separate declines from overdrafts. If the bank declines a debit purchase for insufficient funds, you may avoid an overdraft fee, but you still face the merchant problem: unpaid groceries, a failed bill, or a returned payment fee from a biller. Protection is trying to solve that friction. The question is whether the price of solving it is rational for your pattern of shortfalls.
When overdraft coverage can be a useful safety net
Overdraft tools help most when shortfalls are rare, small, and accidental. Examples include a timing mismatch between a rent draft and a paycheck, a forgotten subscription posting the same day as a larger bill, or a deposit that posts later than expected. In those cases, paying a fee once may cost less than a landlord late fee, a reconnect charge, or the cascading damage of a returned mortgage payment.
Linked-account protection is often the cleaner version of the safety net. If you keep a buffer in savings and authorize transfers to cover checking shortfalls, you are mostly using your own money with possible transfer fees. That structure can be reasonable for people who maintain savings but occasionally mis-time payments. It still requires discipline: repeated transfers without replenishing savings just move the crisis one account over.
People with variable income sometimes use limited overdraft capacity as short-term bridge liquidity. That can work only with a repayment plan and a hard personal rule about frequency. If you need the bridge every pay cycle, you do not have a safety net. You have a structural budget gap.
How the expensive trap usually forms
The trap begins when overdraft stops being an exception and becomes part of monthly cash flow. Multiple fees in a short window can exceed the size of the original shortfall. Some banks historically charged per item, which meant several small debit card purchases could each trigger a fee even if the total overspend was modest. Policies have evolved at many institutions, but you still must read your bank's current schedule rather than assume old headlines or new promises.
Extended overdraft fees or sustained negative-balance charges can add another layer if the account stays negative for days. That turns a one-day mistake into a multi-day bill. Meanwhile, the negative balance still needs to be repaid, so the next paycheck is partially spoken for before it arrives. The cycle becomes familiar: deposit, fees, essential bills, shortfall, fees again.
Behavioral design plays a role. Instant card purchases feel small. Fees arrive later on a statement line that is easy to ignore until the total stings. If alerts are off and balances are checked rarely, people discover the damage after several transactions have already posted. Convenience without visibility is how a safety feature becomes a subscription to mistakes.
There is also an opportunity-cost trap. Money spent on repeated overdraft fees cannot build an emergency fund. Households can spend hundreds of dollars a year on fees that would have covered a modest buffer capable of preventing most overdrafts in the first place. At that point the product is financing a problem it also helps perpetuate.
Fee math you should run with your own numbers
Pull six to twelve months of statements and count overdraft and transfer fees. Total them. Compare that annual total with the cost of alternatives: a twenty-dollar-a-month automatic savings transfer, a no-overdraft account that declines transactions, or a small personal line of credit used rarely and repaid immediately. If fees already exceed what a buffer would have required, the economic case for changing course is strong.
Look at clustering. Did fees hit around the same week each month? That pattern usually points to bill timing rather than random bad luck. Moving due dates, splitting direct deposit, or keeping a one-week expense buffer in checking often removes more pain than arguing with the fee after the fact.
Ask your bank how it orders transactions and whether it caps fees per day. Processing order can affect whether multiple items trigger multiple fees. Caps help, but a capped bad day is still expensive if bad days are frequent. Get answers in writing through the fee schedule and account disclosures, not only through a chat summary.
Safer habits that reduce the need for overdraft
Build a checking floor. Many people sleep better when checking never drops below a set amount such as one week of expenses or a flat dollar cushion. Automate a small transfer into that cushion until it exists. Then treat dipping below the floor as an early warning, not as permission to spend to zero.
Use real-time alerts for low balances, large transactions, and deposits. An alert that arrives before you buy lunch can prevent a fee more effectively than any protection product. Pair alerts with a weekly five-minute balance review, especially in weeks with rent, insurance, or tuition drafts.
Align bills with payday. If rent clears two days before payday and you regularly run thin, ask whether due dates can move, or schedule a holding transfer from savings the day before. Timing fixes are dull and powerful. They address the mismatch that overdraft products monetize.
Separate spending money from bill money. Some households use two checking accounts or sub-accounts: one for fixed bills funded on payday, one for variable spending. When the spending account is empty, spending stops without threatening rent. That structure replaces overdraft theater with visible limits.
Account features and bank choices that change the equation
Some banks and credit unions offer accounts with no overdraft fees that simply decline debit purchases when funds are insufficient. That can be ideal if your main risk is impulse card spending and you can handle an occasional decline. It is less ideal if automatic ACH bills are the issue, because a returned payment may still create merchant fees.
Overdraft lines of credit, where available, charge interest instead of flat fees. Interest can be cheaper for a short bridge that you repay quickly, or more expensive if the balance lingers. Read APR, transfer rules, and whether the line encourages chronic borrowing. A line of credit is still debt.
Early direct deposit features and faster payment posting can shrink the timing gaps that cause overdrafts. They are not magic, and advance access to wages can create its own payday-loan style habits if you spend money before the official pay date. Used carefully, faster posting reduces false shortfalls.
How to decide: net, trap, or redesign
Keep or enable protection if shortfalls are rare, you understand the exact fees, you have a repayment habit, and the alternative decline would create larger costs. Prefer linked savings transfers over repeated flat overdraft fees when you actually maintain savings. Review the feature annually the same way you would review insurance.
Turn it off or switch account types if fees recur monthly, if multiple fees cluster around discretionary spending, or if the negative balance routinely lasts more than a day or two. Recurring use is data. It says your cash cushion and bill calendar need redesign more than your account needs a bigger safety net.
If you are in the trap already, start with a thirty-day stabilization plan. List every autopay, move due dates where possible, pause nonessential subscriptions, and park a starter buffer even if it is small. Call the bank and ask about fee refunds for a first occurrence, hardship programs, or switching to a decline-only account. Then measure fees next month. Progress is fewer fees, not perfect prediction.
Conversations worth having with your bank
Ask which transactions can overdraft, whether ATM and one-time debit overdrafts require opt-in, what the per-item fee is, whether there is a daily cap, how linked transfers work, and how quickly a deposit cures a negative balance. Confirm whether peer-to-peer payments, authorization holds from gas stations or hotels, and recurring debit authorizations are treated differently.
If you opt out of debit card overdraft coverage, understand what will decline and what ACH bills might still overdraft under other rules. Opting out is not always identical to eliminating every possible overdraft scenario. Precision beats slogans.
Special cases: students, joint accounts, and gig income
Students and new graduates often face thin margins and irregular first paychecks. For them, a decline-only account plus a tiny starter buffer can teach clearer limits than repeated fee forgiveness cycles. Parents who help with money should be careful about enabling fee habits while trying to help.
On joint accounts, overdraft risk is shared in practice even when only one person made the purchase. Both owners should agree on whether protection is on, who monitors alerts, and how quickly a negative balance must be cured. Silence about fees is how joint accounts accumulate blame.
Gig workers with lumpy deposits should size buffers to their slowest typical week, not their best week. Overdraft protection cannot substitute for a volatility reserve. If income lands unpredictably, keep essential bills in a separate account funded on purpose when payouts arrive.
The bottom line
Overdraft protection is neither universally helpful nor universally predatory in every household. It is a priced product that solves a cash-timing problem. Used rarely, with linked savings and strong alerts, it can be a rational backstop. Used monthly as invisible income, it becomes an expensive trap that blocks the very buffer that would make it unnecessary.
Your statements already contain the verdict. If overdraft fees are occasional and shrinking, the safety net may be doing its job. If they are frequent and familiar, redesign the budget, the buffers, and possibly the account type. The goal is not to win an argument about bank fees. The goal is a checking account that funds your life without charging you repeatedly for running near empty.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
James Johnson has 10+ years in fintech. He holds an MBA and an MS in Information Technology, and writes about how AI and personal finance actually meet for everyday investors.









Comments (0)