

10-Year Treasury Yield Hits 5%: What It Means for Mortgages, Savings, Bonds, and Stocks
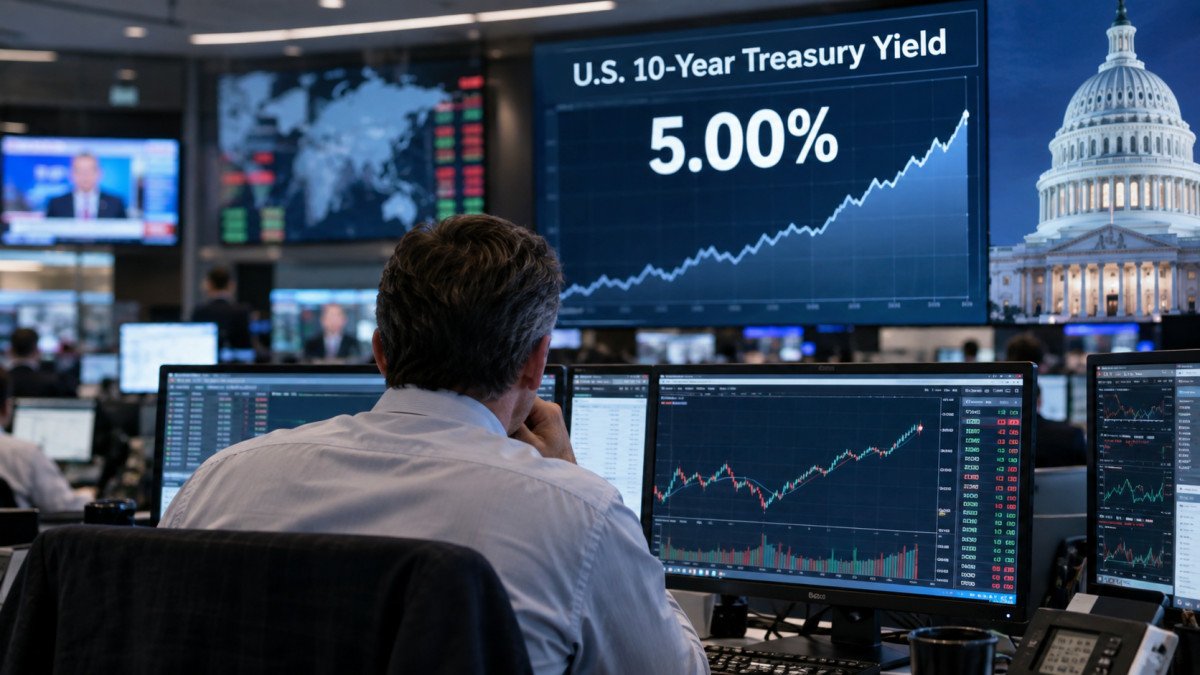
The yield on the benchmark 10-year U.S. Treasury note crossed 5% on September 14, 2026, reaching its highest level since October 2023. Reuters reported an intraday yield of approximately 5.004%, although the figure may move above or below 5% throughout the trading session.
Five percent is not a magical line that automatically triggers a financial crisis. However, it is an important psychological and financial threshold because the 10-year Treasury yield influences borrowing costs, investment valuations, mortgage rates, corporate financing, and the relative attractiveness of stocks and bonds.
The move arrives immediately before the Federal Reserve’s September 15–16 meeting. Investors have increasingly expected policymakers to raise the federal funds rate as persistent inflation and rising energy prices complicate the economic outlook. The Fed’s official calendar confirms that its decision is scheduled for September 16.
For households, investors, savers, and prospective homebuyers, the important question is not simply whether the yield touched 5%. It is what happens if borrowing costs remain elevated.
Why the 10-year Treasury yield matters
A Treasury yield represents the return investors demand to lend money to the federal government. The 10-year note is particularly important because it serves as a benchmark for many other interest rates and financial assets.
It can influence:
- Fixed mortgage rates
- Corporate borrowing costs
- Auto and personal-loan pricing
- Bond prices and yields
- Stock-market valuations
- Government interest expenses
- Rates offered on some savings products and certificates of deposit
The 10-year yield does not directly determine every consumer interest rate. For example, the Federal Reserve does not set mortgage rates. Nevertheless, movements in Treasury yields frequently affect the broader market conditions lenders use when pricing loans.
Why Treasury yields are rising
Bond prices and yields move in opposite directions. When investors sell existing Treasury securities, their prices generally decline and their effective yields rise.
Several forces are contributing to the current increase.
First, investors are concerned that inflation may remain above the Federal Reserve’s 2% target. Rising energy prices can increase transportation, production, and household expenses, while persistent service-sector inflation may prove harder to reverse.
Second, markets are preparing for the possibility of another Federal Reserve rate increase. Although the federal funds rate is a short-term rate and the 10-year Treasury is a long-term security, expectations about future monetary policy influence yields across the market.
Third, investors may demand greater compensation for holding long-term government debt when the inflation outlook is uncertain. Federal borrowing requirements and the supply of Treasury securities can also influence the return investors require.
The result is a higher-for-longer interest-rate environment that may affect borrowers and investors differently.
What a 5% Treasury yield means for mortgage rates
The clearest effect for many households may appear in the mortgage market.
Thirty-year fixed mortgage rates often move in the same general direction as the 10-year Treasury yield, although the two rates do not move in perfect alignment. Mortgage-backed securities, lender competition, credit risk, loan demand, and market volatility also affect the final rates offered to borrowers.
On September 14, one reported national average for a 30-year fixed mortgage was approximately 6.90%, while another widely followed measure had recently moved slightly above 7%.
If Treasury yields remain close to or above 5%, a rapid return to substantially cheaper mortgages becomes less likely.
Prospective buyers should avoid assuming that the Federal Reserve’s next announcement will immediately reduce mortgage rates. Even if the Fed holds its policy rate steady, longer-term yields could remain elevated if investors continue to worry about inflation.
Buyers who remain in the market can focus on decisions within their control:
- Compare written loan estimates from multiple lenders.
- Evaluate the payment rather than concentrating only on the purchase price.
- Ask how long a quoted rate is locked.
- Understand the cost and break-even period of discount points.
- Maintain sufficient savings after closing.
- Avoid stretching the budget based on an assumed future refinance.
A refinance may eventually become available, but it should be treated as a future possibility—not as the foundation of today’s affordability calculation.
What it means for savings accounts and CDs
Higher market yields can be favorable for savers, particularly when banks and credit unions are competing for deposits.
High-yield savings accounts, money-market deposit accounts, certificates of deposit, Treasury bills, and money-market funds may continue offering relatively attractive returns if interest rates remain elevated.
However, consumers should not assume that every bank will automatically increase its savings rate. Deposit rates can vary substantially, and traditional savings accounts at large institutions may still pay very little.
Savers should compare:
- Annual percentage yield
- Minimum-balance requirements
- Monthly fees
- Withdrawal restrictions
- Early-withdrawal penalties
- Federal deposit-insurance coverage
- Whether a promotional rate can change after a short period
People who do not need immediate access to all their cash might consider dividing funds across different maturities instead of locking everything into one long-term CD. A CD ladder can preserve periodic access to money while capturing available yields.
Emergency savings should generally remain accessible. A slightly higher return is rarely worth making essential cash difficult or expensive to reach.
What happens to existing bonds when yields rise
When newly issued bonds offer higher yields, older bonds paying lower rates become less attractive. Their market prices usually decline to compensate investors for their smaller payments.
That does not necessarily mean every bondholder permanently loses money.
An investor who owns an individual Treasury security and holds it until maturity generally continues receiving the promised payments, assuming the security is not sold early. A bond fund, however, continuously holds and replaces securities, so its market price can fluctuate as rates change.
Duration is an important factor. Long-duration bond funds are generally more sensitive to changes in interest rates than short-duration funds. A sharp increase in yields can therefore produce larger price declines in long-term bond portfolios.
Investors should check what they actually own before reacting:
- Individual bonds or a bond fund
- Short-, intermediate-, or long-duration holdings
- Government, municipal, or corporate debt
- Investment-grade or high-yield securities
- Money needed soon or money invested for a long-term objective
Selling solely because a bond fund has declined can turn a temporary price change into a realized loss. At the same time, investors who need money in the near future should not ignore interest-rate risk.
Why a 5% yield can pressure stocks
Stocks compete with bonds for investor capital.
When government securities offer higher yields, investors can earn more income from assets generally considered less risky than stocks. That can make expensive equities less attractive, especially when their valuations depend heavily on profits expected far in the future.
Growth and technology companies can be particularly sensitive to rising yields. Higher discount rates reduce the present value investors assign to future earnings. Businesses that depend on borrowing may also face higher financing costs.
This does not mean that a 5% Treasury yield guarantees a stock-market crash. Corporate earnings, economic growth, productivity, investor sentiment, and company-specific results still matter.
The speed of the yield increase may be as important as the level itself. A gradual adjustment gives markets and businesses more time to adapt. A rapid and disorderly move can produce greater volatility.
Long-term investors should be cautious about making major portfolio changes based on a single market session. A diversified allocation should be designed to survive changing interest-rate environments.
What retirement investors should consider
Retirees and people approaching retirement may experience both sides of higher yields.
The positive side is that high-quality bonds and cash-equivalent investments may generate more income than they did during the extremely low-rate years. Investors may not need to accept as much credit or stock-market risk to pursue a particular income target.
The negative side is that existing long-duration bonds can decline in value, while stock portfolios may become more volatile.
Retirement investors can review:
- How much money will be needed during the next one to three years
- Whether near-term withdrawals depend on selling volatile assets
- The duration and credit quality of bond holdings
- The concentration of the portfolio in high-valuation growth stocks
- Whether the current allocation still matches the investor’s risk tolerance
A cash reserve for near-term expenses can reduce the risk of having to sell stocks or long-term bonds during a market decline. However, holding excessive cash for many years can create inflation and opportunity-cost risks.
Should investors buy 10-year Treasuries at 5%?
A 5% yield may be appealing, but it should not be viewed as an automatic buying signal.
An investor purchasing a 10-year Treasury can lock in a stated stream of interest and principal payments if the security is held to maturity. But its market price may decline if yields rise further. The investor also gives up the opportunity to reinvest that money at higher rates during the holding period.
Before purchasing, consider:
- When the money will be needed
- Whether the security will likely be held until maturity
- How the Treasury fits within the overall portfolio
- Whether shorter maturities offer sufficient returns with less price sensitivity
- The tax treatment of Treasury interest
- The possibility that inflation reduces the investment’s real return
Treasury securities may be appropriate for stability and income, but the maturity should match the investor’s financial timeline.
What consumers should do now
The most useful response is usually a review—not a prediction.
Borrowers can compare rates and avoid taking on payments that require interest rates to decline later. Savers can verify whether their cash is earning a competitive return. Investors can examine duration, diversification, and the amount of money exposed to short-term market volatility.
It is also important not to overreact to the round number itself. The difference between a 4.99% and 5.00% yield is economically small. The significance comes from what the level represents: persistent inflation concerns, more expensive borrowing, and renewed competition between stocks and bonds.
The bottom line
The 10-year Treasury yield reaching 5% is an important market development because it can affect mortgages, savings products, bonds, stocks, and retirement portfolios.
For homebuyers, it reinforces the need to calculate affordability using current rates. For savers, it may extend the opportunity to earn meaningful interest on cash. For bond investors, it creates better prospective yields but may produce additional price volatility. For stock investors, it raises the return companies must compete against.
The next major development will be the Federal Reserve’s September 16 policy announcement. Until then, forecasts remain forecasts. Consumers and investors should base decisions on their own timelines and financial capacity—not on the assumption that one central-bank meeting will immediately reverse today’s interest-rate environment.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.









Comments (0)