

How the HSA Triple Tax Advantage Actually Works
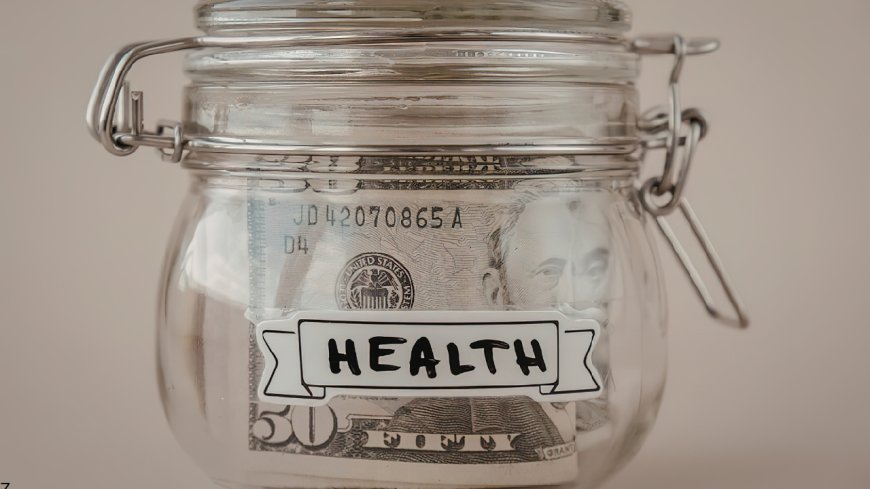
Why the HSA gets so much attention from careful planners
A Health Savings Account (HSA) is one of the few accounts in the U. S.
tax code that can deliver three distinct tax benefits in the same year. That combination—often called the triple tax advantage—is why many personal-finance educators treat the HSA as more than a medical spending wallet.
Used well, it can also become a long-horizon investing account that sits alongside a 401(k) or IRA. This article walks through each leg of the advantage, the eligibility rules that unlock it, and the practical choices that determine whether you actually capture the full benefit.
It is educational tax-and-accounts framing, not medical or clinical advice.
What “triple tax advantage” means in plain English
The three advantages are: Contributions can reduce taxable income. Amounts you contribute (within annual limits) are generally pre-tax through payroll or deductible if you contribute after-tax outside payroll, subject to IRS rules for your filing situation.
Earnings can grow tax-deferred. Interest, dividends, and capital gains inside the HSA are not taxed year to year while they remain in the account.
Qualified medical withdrawals can be tax-free. Distributions used for IRS-qualified medical expenses are generally not included in taxable income.
Very few accounts stack all three. A traditional 401(k) or IRA typically helps on contributions and growth, then taxes withdrawals.
A Roth helps on growth and qualified withdrawals, but contributions are after-tax. An HSA, for someone who qualifies and uses it carefully, can sit in a rare middle category.
Eligibility: the high-deductible health plan gate
You generally cannot contribute to an HSA unless you are covered by a qualifying high-deductible health plan (HDHP) and you are not covered by other disqualifying coverage. The IRS publishes annual HDHP deductible and out-of-pocket maximum thresholds.
Those numbers change, so treat them as moving targets you verify each year rather than memorizing once. Other common eligibility constraints include not being claimed as a dependent and not having Medicare coverage in a way that blocks HSA contributions.
Timing matters: contribution eligibility is often framed around months of qualifying coverage, with catch-up contribution rules for those age 55 and older. If you lose HDHP eligibility mid-year, contribution room usually shrinks accordingly.
That is one reason HSA planning is annual, not “set and forget.”
Contribution limits and the family vs. self-only distinction
Each year the IRS sets separate contribution ceilings for self-only and family HDHP coverage. Employer contributions count toward the same overall limit.
Catch-up contributions for age 55+ are an add-on for the account holder who qualifies. Practically, that means: Confirm your coverage type (self-only vs.
family) before you set payroll deferrals. Count employer seed money or match-like HSA deposits toward the annual ceiling.
If you contribute outside payroll, keep records that support the deduction on your return. Overcontributing creates cleanup work—excess contributions and earnings can face tax consequences if not corrected under IRS procedures.
The educational takeaway: treat the limit as a hard budget, not a soft target.
Advantage 1: Tax-advantaged contributions
When contributions come out of payroll on a pre-tax basis, they typically reduce wages subject to federal income tax and, in many cases, FICA—depending on how the plan is administered. That payroll path is often the cleanest way to capture the front-end benefit.
If you contribute with after-tax dollars, you may still claim an above-the-line deduction (subject to eligibility and limits). Either path can lower taxable income relative to funding medical costs from a taxable checking account.
Advantage 2: Tax-free growth inside the account
Once money is in the HSA, it can sit in cash or be invested, depending on your custodian’s menu. Growth is not taxed annually.
That is why people who can pay current medical bills from cash flow sometimes choose to invest HSA balances and let receipts age—more on that strategy below. Custodian fees, investment expense ratios, and cash “sweeps” still matter.
Tax advantage does not erase product costs.
Advantage 3: Tax-free qualified withdrawals
Withdrawals used for qualified medical expenses are generally tax-free at any age. The IRS defines which expenses qualify; common categories include many deductibles, copays, coinsurance, and certain other medical costs.
Keep documentation. The tax benefit is only as strong as your records.
Non-qualified withdrawals before age 65 are generally taxable and may face an additional tax. After 65, non-qualified withdrawals are typically taxable like traditional retirement-account distributions, but without the extra penalty that applies earlier.
That age rule is why some planners describe an HSA as eventually behaving more like a flexible medical-retirement hybrid.
HSA vs. FSA: related names, different designs
Flexible Spending Accounts (FSAs) are often confused with HSAs because both can help with medical costs. The differences that matter for education: Use-it-or-lose-it pressure is a classic FSA feature (with limited carryover or grace-period exceptions depending on the plan).
HSAs are designed to roll over indefinitely. Portability: HSAs are owned by the individual and generally move with you.
FSAs are typically employer-plan accounts with tighter exit rules. Investment: Many HSAs allow investing once a cash threshold is met.
FSAs are usually spending accounts, not long-term investment vehicles. Eligibility link: HSAs require an HDHP.
FSAs do not use the same gate. If your employer offers both, coordination rules can be strict.
A limited-purpose FSA (for dental/vision, for example) is sometimes paired with an HSA; a general-purpose FSA can block HSA contributions. Read the plan documents before assuming you can run both at full strength.
Strategy choice: spend now vs. invest and reimburse later
Two coherent approaches show up repeatedly among careful users: Pay medical costs from the HSA as they occur. This maximizes the tax-free withdrawal benefit immediately and keeps bookkeeping simple.
It is often the right fit when cash flow is tight or when the HSA balance is still small. Pay medical costs out of pocket, invest the HSA, and reimburse yourself later.
IRS rules generally allow you to reimburse qualified expenses incurred after the HSA was established, even years later, if you kept receipts. That can turn the HSA into a long-term investment account while preserving the option of tax-free withdrawals.
It requires discipline, recordkeeping, and enough non-HSA cash to cover today’s bills. Neither approach is universally “best.”
The educational point is that the triple tax advantage is a design feature; your household cash flow and documentation habits determine how much of it you actually use.
Investing inside an HSA: same principles, different wrapper
If you invest HSA dollars, the portfolio logic looks familiar: diversification, costs, time horizon, and risk tolerance. The wrapper is different because qualified medical withdrawals can be tax-free, which changes how some people think about asset location—but you do not need exotic tactics to benefit.
Practical checklist: Know the custodian’s investment threshold and fund list. Prefer low-cost broad funds if you are building a long-term sleeve.
Keep enough cash for near-term expected medical costs if you plan to spend from the account soon. Revisit beneficiaries; HSAs have their own death-distribution rules.
Common mistakes that quietly erase the advantage
Contributing without confirming HDHP eligibility for the contribution months. Ignoring employer deposits when calculating remaining room.
Taking non-qualified withdrawals without understanding the tax and potential extra tax before 65. Letting a high-fee cash account sit for years when an investment option was available and appropriate.
Mixing up HSA rules with FSA or HRA rules during open enrollment. Failing to keep receipts if you plan delayed reimbursement.
How an HSA fits next to a 401(k) or IRA
Think in layers. Capture any true employer 401(k) match first if it exists—that is an immediate return.
Then compare: HSA contribution (if eligible and you value the triple benefit), traditional vs. Roth retirement deferrals, taxable investing, and cash reserves.
Households with high medical exposure may prioritize HSA funding differently than households with low expected near-term medical costs. The HSA is not a substitute for an emergency fund in a taxable account.
Medical liquidity and general emergency liquidity solve overlapping but not identical problems.
A simple annual review routine
Once a year—ideally during open enrollment and again at tax time—review: HDHP eligibility and contribution ceiling for the year. Employer contribution amount already made or promised.
Payroll deferral rate vs. remaining room.
Whether you are in “spend” mode or “invest and receipt” mode. Investment allocation and fees.
Beneficiary designations. That routine keeps the triple tax advantage from becoming a slogan you never operationalize.
Bottom line
The HSA’s reputation comes from a real structural edge: potential tax benefit on the way in, tax-advantaged growth, and tax-free qualified medical withdrawals. Eligibility hinges on an HDHP and related IRS rules.
Contribution limits are annual and shared with employer deposits. The biggest practical fork is whether you spend from the account now or invest and reimburse later with documentation.
Pair those mechanics with ordinary investing discipline, and the HSA can serve both near-term medical funding and long-horizon planning—without turning a tax account into medical advice.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.










Comments (0)