

The 50/30/20 Budget Reimagined for Today’s Cost of Living
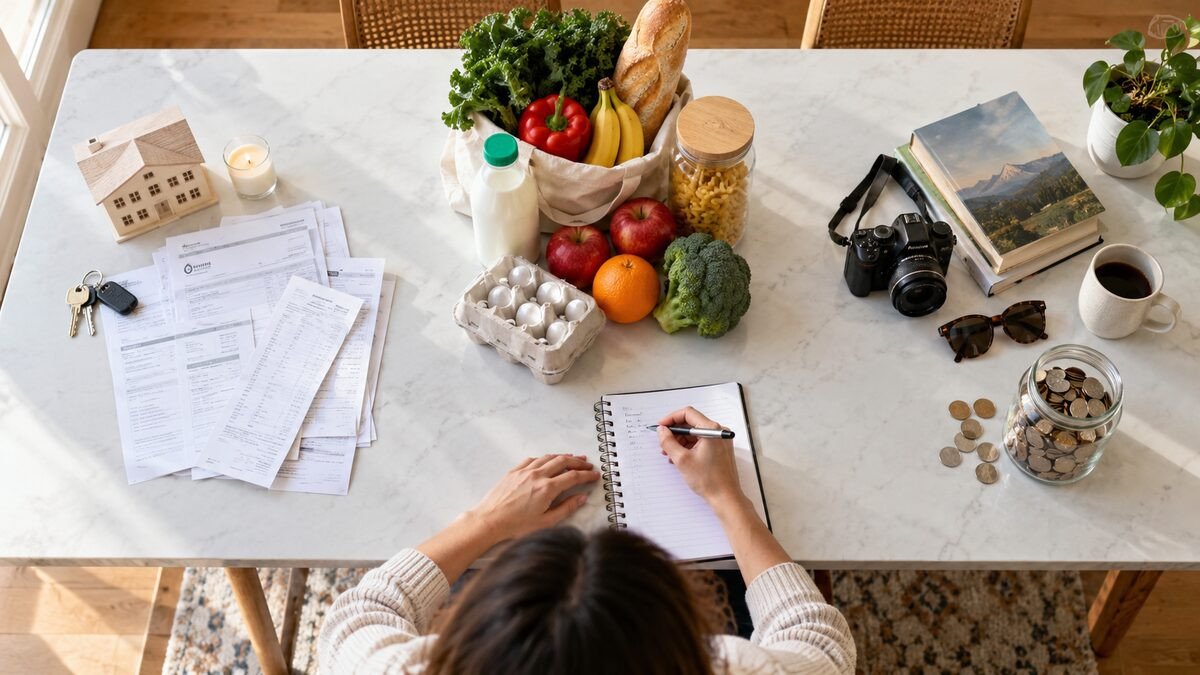
The 50/30/20 budget divides take-home pay among needs, wants, and savings or debt goals. It is a starting framework, not a moral scorecard. In a high-cost city, needs may exceed 50 percent through no lack of discipline.
A modern version keeps the categories but treats the percentages as flexible targets, then uses trends to guide better decisions.
Define take-home pay consistently
Start with income available after taxes and payroll deductions. Record retirement contributions that already leave the paycheck so savings is not understated.
For variable income, use a conservative baseline and assign excess income separately.
Separate needs from commitments
Housing, basic food, utilities, insurance, work transportation, and minimum debt payments are needs. A contract does not automatically make an expense essential.
The distinction is about protecting health, housing, work, and legal obligations.
Use ranges, not rigid numbers
A household might operate at 60/20/20 while working toward lower fixed costs. The useful question is whether essentials are crowding out resilience.
Document the reason for a temporary deviation and set a review date.
Protect the future category
Savings can include emergency reserves, retirement, and planned irregular expenses. Debt payments above the minimum also strengthen the balance sheet.
Automate a realistic amount on payday, even if it starts below 20 percent.
Adjust the largest levers
Housing, transportation, insurance, and recurring services usually matter more than minor treats. Quote insurance and audit subscriptions.
Small cuts help, but they should support rather than distract from larger decisions.
The bottom line
Use 50/30/20 as a dashboard. Measure where money goes, choose workable targets, and improve one category at a time.
A budget should create clarity and resilience, not shame.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.










Comments (0)