

Debt Avalanche vs. Debt Snowball: Comparing the Math and the Behavior
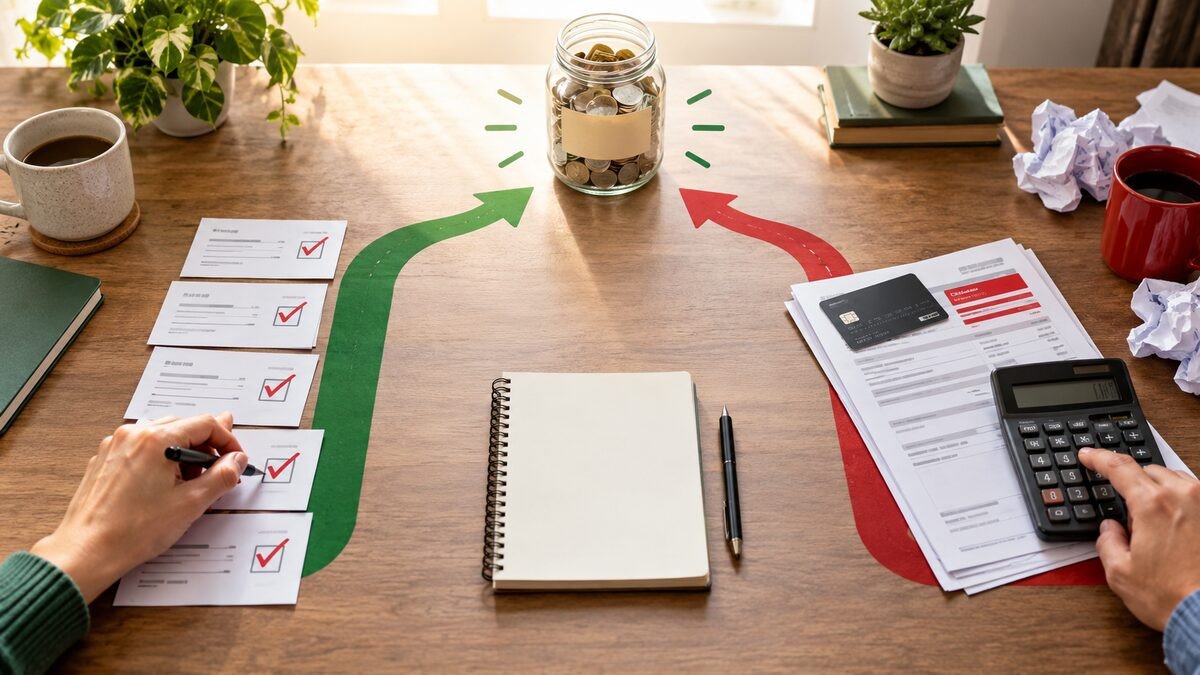
Two methods, one shared engine
When you carry multiple debts—credit cards, personal loans, auto loans, student loans—the order you attack them changes how much interest you pay and how quickly you feel progress. Two classic frameworks dominate personal-finance education:
- Debt avalanche: Pay minimums on everything, then put every extra dollar toward the balance with the highest interest rate.
- Debt snowball: Pay minimums on everything, then put every extra dollar toward the smallest balance, regardless of rate.
Both methods use the same engine: minimum payments everywhere else, focused extra payments on one target, then roll that freed-up payment into the next target. The difference is only the sorting rule. That small difference drives big educational debates about math versus motivation.
Shared setup rules (so comparisons stay fair)
For any clean comparison, assume:
- You list every debt with balance, APR (or interest rate), and minimum payment.
- You stop adding new revolving balances (or the math becomes a moving target).
- You pick a fixed monthly budget for total debt payments above the sum of minimums.
- When a debt is cleared, its former payment joins the extra pile for the next target (“rolling” payments).
If income is unstable or minimums already consume the budget, neither method can create magic. The first educational step is confirming that a surplus exists—or that expenses can be cut—to fund acceleration.
How the avalanche works
Sort debts from highest interest rate to lowest. Example teaching list:
Example debt details
- Card A: $4,000 balance, 24% APR, and a $120 minimum payment.
- Card B: $6,500 balance, 19% APR, and a $160 minimum payment.
- Personal loan: $8,000 balance, 11% APR, and a $200 minimum payment.
- Auto loan: $12,000 balance, 6% APR, and a $280 minimum payment.
Avalanche order: Card A → Card B → personal loan → auto loan.
Every month you pay all minimums, then send every extra dollar to Card A until it hits zero. Then Card B inherits Card A’s minimum plus the extra, and so on.
Why the math prefers this: Interest accrues as rate × balance. Clearing the costliest rate first usually minimizes total interest dollars over the life of the payoff plan, all else equal.
How the snowball works
Sort by balance, smallest to largest (ties broken however you like—often by rate). Using the same example, snowball order becomes: Card A ($4,000) → Card B ($6,500) → personal loan → auto loan.
In this particular example, avalanche and snowball start on the same debt because the smallest balance also has the highest APR. Real life is messier. Change Card A to $9,000 at 24% and add a $1,200 store card at 15%, and snowball starts on the store card while avalanche still starts on the 24% balance.
Why behavior prefers this: Smaller balances reach zero sooner. Each closure is a visible win—fewer bills, a psychological “scoreboard” reset—that helps some people stick with the plan long enough to finish.
A worked mini-example with divergent ordering
Consider three debts and $700 total available each month for debt (including minimums):
Debt details for this comparison
- Store card: $1,200 balance, 15% APR, and a $40 minimum payment.
- Credit card: $5,000 balance, 22% APR, and a $125 minimum payment.
- Personal loan: $7,500 balance, 10% APR, and a $180 minimum payment.
Minimums total $345, so $355 is the monthly “extra” plus the rolling effect as debts clear. (Exact amortization depends on issuer minimum formulas; we will use directional math for teaching.)
Avalanche order: Credit card (22%) → store card (15%) → personal loan (10%).
Snowball order: Store card ($1,200) → credit card ($5,000) → personal loan ($7,500).
Directional interest logic
The credit card charges roughly 22% annually on ~$5,000—about $1,100 per year if the balance barely moved—while the store card’s 15% on $1,200 is about $180 per year. Every month the high-rate balance survives, it generates more interest dollars than the small mid-rate balance. Avalanche attacks that expensive generator first.
Snowball may clear the $1,200 store card in a handful of months by throwing the full extra at it. That frees $40 (its minimum) plus momentum. Meanwhile the $5,000 at 22% kept accruing. Whether snowball “costs” a few hundred dollars more in interest depends on the spreads, balances, and how large your extra payment is—but the direction is consistent: avalanche usually wins on interest; snowball often wins on time-to-first-victory.
A simplified interest gap illustration
Suppose your focused extra is large enough that either method finishes all three debts in roughly the same overall number of months—just in different orders. Even then, the path that carries the 22% balance longer will typically accumulate more interest. If snowball clears the store card in 3 months while avalanche takes 8–10 months to reach that small balance, snowball feels faster early, yet avalanche may still reduce total interest by keeping pressure on 22% debt from day one.
You can replicate this with any amortization spreadsheet: same payment budget, two sort keys, compare total interest and months to debt-free. That exercise is more educational than memorizing slogans.
When avalanche is the clearer fit
Avalanche tends to fit when:
- Rate gaps are wide (for example, 25% cards vs. 6% auto loan).
- Balances are large enough that interest differences compound into real money.
- You are motivated by optimization and will not quit if the first payoff takes longer.
- You can automate payments so willpower is less of a bottleneck.
If your highest-rate debt is also enormous, avalanche’s first win may take a long time. Some people hybridize (see below) rather than abandon rate priority entirely.
When snowball is the clearer fit
Snowball tends to fit when:
- Past plans failed because progress felt invisible.
- You have several tiny balances creating mental clutter and fee risk.
- Rate differences are modest, so the interest “penalty” for snowball is small.
- You need early proof that the system works to stay consistent.
Behavioral finance research often finds that motivation and follow-through can outweigh small mathematical gaps. Paying an extra few hundred dollars in interest can still be a rational personal outcome if the alternative is quitting and revolving debt for years.
Minimum payments, fees, and APR traps to watch
- Credit card minimums are often a percentage of balance plus interest/fees, so they shrink slowly if you pay only the minimum—another reason focused extras matter.
- Penalty APRs and late fees can overwhelm tidy avalanche/snowball math. On-time minimums are non-negotiable infrastructure.
- 0% intro APR balances that will reprice later may deserve special treatment: sometimes it is rational to clear a soon-to-reprice balance before a slightly higher but stable rate, depending on timelines. That is a judgment overlay on top of pure avalanche sorting.
- Variable rates mean your “highest rate” ranking can change; review the order quarterly.
Student loans, mortgages, and “good debt” framing
Avalanche vs. snowball debates usually focus on consumer debts. Low-rate mortgage debt is often treated separately because of size, tax considerations (for those who itemize), and the opportunity cost of diverting money from investing. Federal student loans may have unique IDR, forgiveness, or forbearance features that change priorities. Educational takeaway: sort comparable debts with avalanche/snowball; do not blindly include every liability in the same stack without reading the loan rules.
Hybrid approaches that keep the math mostly honest
You do not have to pick a pure ideology:
- Snowball for the first small win, then avalanche. Clear one or two tiny balances for momentum, then switch to highest rate.
- Avalanche with a “nuisance debt” exception. Knock out a $300 medical bill or annual-fee card to simplify life, then return to rate order.
- Highest rate among debts above a balance threshold. Ignore micro-balances until later—or clear them first if they create fees.
Hybrids acknowledge that humans run the plan.
How investing vs. debt payoff intersects (briefly)
If you have employer 401(k) match, capturing the match usually beats accelerating low-rate debt because the match is an immediate return. High-APR credit card debt typically outranks speculative investing because a 20%+ guaranteed “return” from paying the card is hard to match after tax and risk. Mid-rate debts sit in a gray zone that depends on interest rate, investment expected returns, risk tolerance, and cash reserves. Avalanche/snowball answer order among debts; they do not fully answer debt versus investing.
Building your one-page payoff plan
- List debts: balance, rate, minimum, due date.
- Choose avalanche, snowball, or a written hybrid rule.
- Set a monthly total payment number you can sustain for 12 months.
- Automate minimums; manually or automatically send extras to the current target.
- When a debt closes, roll its payment and celebrate in a way that does not create new debt.
- Recalculate rankings if rates change materially.
Track progress with a simple chart of total balance monthly. Visibility supports either method.
Bottom line
Avalanche and snowball share the same payment-rolling structure; they differ in sort order. Avalanche usually minimizes interest by attacking the highest APR first. Snowball usually maximizes early psychological wins by clearing the smallest balances first. The “best” method is the one that matches your rate spreads and the behavior you will maintain. Run the numbers once, pick a rule you can explain in one sentence, and let consistency—not perfection—finish the schedule.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
James Johnson has 10+ years in fintech. He holds an MBA and an MS in Information Technology, and writes about how AI and personal finance actually meet for everyday investors.










Comments (0)