

Why Debt Payoff Plans Fail: Snowball, Avalanche, or a Hybrid?
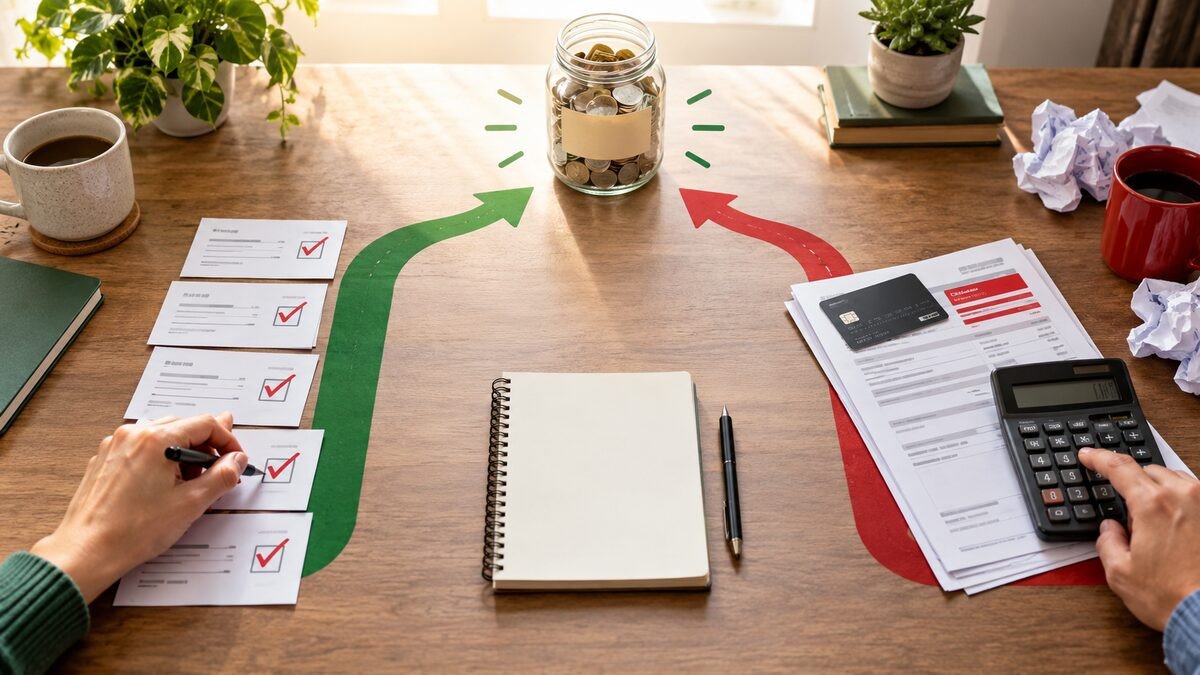
Paying off several debts is partly a math problem and partly a behavior problem. The debt avalanche targets the highest annual percentage rate first, while the debt snowball targets the smallest balance. One generally minimizes interest; the other creates faster visible wins. A successful plan must do both things that matter: reduce the cost of debt and keep the borrower engaged long enough to finish.
Start with a complete debt inventory
List every balance, APR, minimum payment, due date and promotional expiration date. Identify whether each rate is fixed or variable and note any deferred-interest offer. A zero-percent balance may look harmless, but it can become urgent if the promotion ends soon or deferred interest can be added retroactively.
Keep minimum payments current on every account. The snowball and avalanche describe where extra money goes; neither method excuses a missed payment elsewhere.
How the debt snowball works
Order debts from the smallest balance to the largest, regardless of APR. Direct all extra money to the smallest while paying minimums on the rest. When that account reaches zero, roll its former payment into the next-smallest balance.
The advantage is momentum. Closing an account quickly reduces the number of monthly bills and gives the borrower evidence that the plan is working. That psychological reinforcement can matter when repayment will take years.
How the debt avalanche works
Order debts from the highest APR to the lowest. Send extra money to the costliest balance, then roll that payment to the next-highest rate. When payments and timing are otherwise identical, this method generally produces the lowest total interest cost.
The tradeoff is that the first payoff milestone can take longer when the highest-rate account also has a large balance. Borrowers who need early wins may find the method harder to sustain even though its mathematics are stronger.
A simple example of the tradeoff
Imagine three debts: a $900 medical balance at 0%, a $3,000 credit card at 24%, and an $8,000 personal loan at 10%. The snowball clears the $900 balance first. The avalanche attacks the 24% card because each dollar paid there prevents more interest.
Neither choice is irrational. The avalanche buys the larger guaranteed interest saving. The snowball removes one obligation quickly and frees its minimum payment. The right choice depends on whether cost efficiency or immediate momentum is more likely to keep the household consistent.
When a hybrid strategy makes sense
A deliberate hybrid can clear one very small balance for momentum and then switch to the highest APR. It can also prioritize a promotional balance shortly before its rate resets. Write the exception into the plan so a reasonable adjustment does not become constant reshuffling.
Review the order only when something material changes: an APR increases, a promotion nears expiration, income changes, or a balance is eliminated. Weekly switching usually creates noise rather than progress.
Protect the plan from emergencies
Using every available dollar for debt can backfire if an ordinary repair immediately returns to a credit card. Keep a starter emergency reserve based on likely near-term expenses, insurance deductibles and income stability. The reserve does not need to be perfect before repayment begins, but zero cash makes the plan fragile.
Make extra payments predictable
Automate minimums when the checking-account balance can support them, then schedule the extra payment shortly after payday. Apply windfalls using a predetermined percentage rather than deciding emotionally each time. Confirm that extra loan payments reduce principal and do not merely advance the next due date.
Lowering the APR can change the payoff order
A borrower with a strong payment history can ask an issuer for a lower APR. Balance transfers or consolidation loans may help, but only when the transfer fee, new rate, term and total cost are favorable. Extending repayment can lower the monthly payment while increasing lifetime interest.
Avoid using consolidation as permission to refill paid-off cards. The plan succeeds only if total debt declines.
How to choose without overthinking it
- Choose the avalanche if minimizing interest is the priority and you can tolerate a longer first milestone.
- Choose the snowball if quick account closures materially improve motivation.
- Choose a written hybrid if one small win or expiring promotion deserves temporary priority.
- Reconsider the plan if minimum payments are unaffordable; reputable nonprofit credit counseling may be appropriate.
The bottom line
The avalanche usually wins the interest calculation, while the snowball can win the consistency battle. A clearly defined hybrid can capture part of both. Protect every minimum payment, maintain a modest cash buffer, stop adding new balances and keep directing the freed payments forward until the final debt is gone.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0

Passionate about breaking down complex finance-related concepts into simple terms to help everyday people.










Comments (0)