Home Warranty Plans: Are They Worth It for an Older Home?
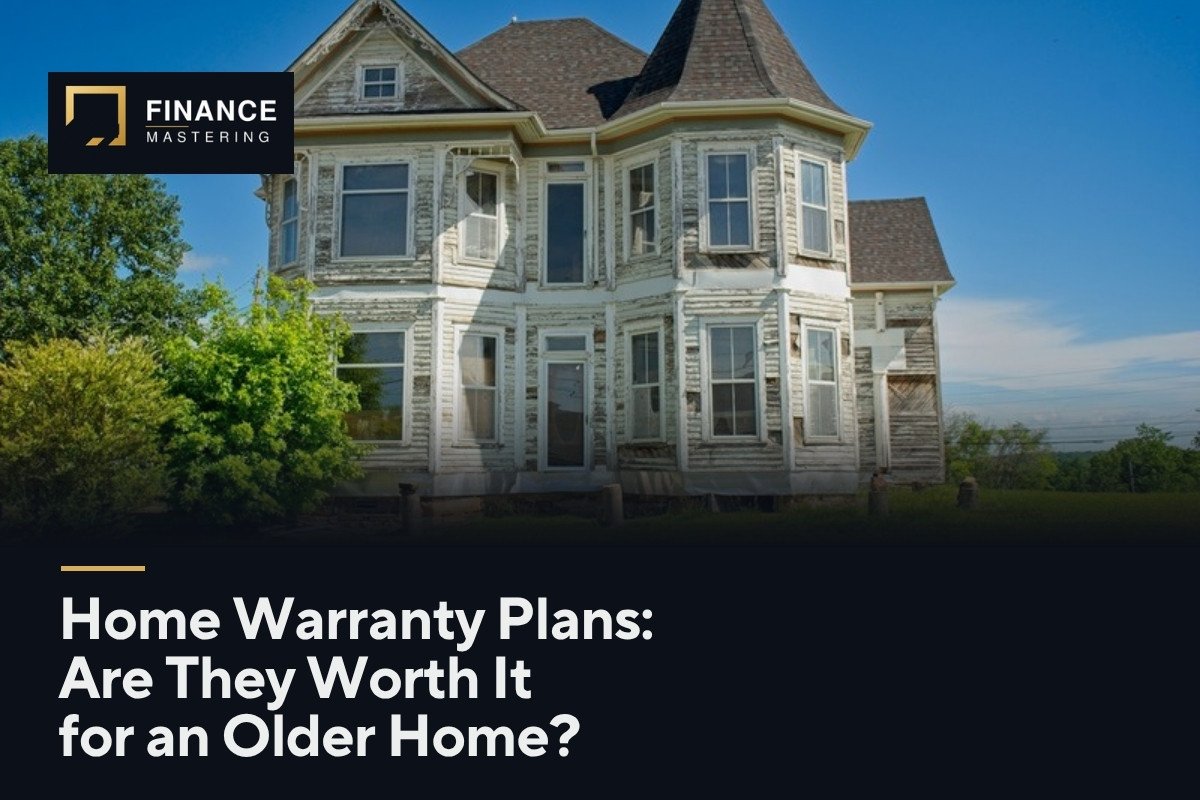
The house was built in 1984, and the sellers have offered to include a one year home warranty at closing. The buyer's agent calls it peace of mind. The buyer looks at the inspection report, which notes a 17 year old air conditioner, an original water heater, and aging plumbing fixtures, and wonders whether the warranty will actually pay for any of it when something fails.
The honest answer is that it depends almost entirely on the contract. A home warranty can help with some repairs in an older home, but the features that make older homes expensive to maintain are often the same features these plans limit or exclude.
What a home warranty actually is
Despite the name, a home warranty is not a manufacturer's warranty and not insurance. The Federal Trade Commission describes home warranties as service contracts, agreements you pay for separately that cover the repair or replacement of certain systems and appliances for a set period.
That framing matters. A manufacturer's warranty comes with a product and is included in the price. A service contract is an extra purchase, and its value depends on what it covers, what it excludes, what it costs each time you use it, and how willing the company is to approve claims. Homeowners insurance is different again, generally covering sudden events like fire or certain storm damage rather than wear and tear.
How the costs add up
A home warranty usually has two kinds of cost. The first is the annual or monthly premium. The second is a service fee, sometimes called a trade call fee or deductible, that you pay each time a technician comes out. The FTC advises buyers to check these fees, along with limits on how much the company will pay.
Here is an illustrative example. Suppose a plan costs $600 a year and charges a $100 service fee per visit. If you file two claims during the year, your total out of pocket cost before any extra charges is $800. If the company pays for a $1,500 air conditioning repair and a $300 dishwasher repair, the plan was worth it that year. If you file no claims, you paid $600 for nothing. If the company denies the larger claim, you paid $700 and still owe the full repair.
These are example numbers, not market averages. Real prices vary widely by company, location, coverage tier, and add-ons. Get written quotes and compare them against the actual repair risks in your house.
The fine print that matters most for older homes
Older homes tend to run into a specific set of contract terms. Read each of these before you buy.
Coverage caps. Many contracts limit how much the company will pay per item, per claim, or per year. A cap that easily covers a dishwasher repair may fall well short of replacing a heating system. The FTC specifically recommends checking reimbursement limits.
Exclusions. The FTC suggests checking whether certain appliances or systems are not included. A safe working assumption is that anything not listed in the contract is not covered. Look closely at items commonly excluded or limited, such as roofs, foundations, structural elements, and certain parts of plumbing and electrical systems.
Pre-existing conditions. Many contracts exclude problems that existed before coverage began. In an older home, it can be hard to prove when a problem started, which creates room for disputes. Ask how the company decides whether a condition was pre-existing.
Maintenance requirements. Some contracts deny claims if the company concludes the system was not properly maintained. For older equipment with no service records, that clause deserves attention. Keep receipts for any maintenance you do after buying.
Code and access costs. Older homes may need code upgrades, permits, or removal of materials to complete a repair. Ask whether the contract covers those added costs or leaves them to you.
Repair versus replace. Contracts often give the company the choice to repair rather than replace, and may limit replacements to comparable equipment or a cash amount. Know who decides and how.
Cancellation terms. The FTC suggests checking whether you can cancel and whether a cancellation fee applies. That matters if the first year shows the plan is not useful.
How claims work in practice
The FTC suggests asking whether the claims process seems difficult or slow, since waiting a long time to get paid back reduces the value of coverage. Many companies require you to use their network of contractors, which means you may not be able to choose your own technician or schedule. Response times can vary, especially for heating and cooling during peak seasons.
Before buying, ask how long approvals typically take, whether you can use your own contractor in an emergency, and what happens if a repair needs a part that is no longer made. It is wise to put claims and complaints in writing and keep copies.
What a claim might look like, as an example
Picture the 1984 house in its first summer. The 17 year old air conditioner stops cooling during a heat wave. The owner calls the warranty company, pays the service fee, and waits for an assigned contractor. The technician reports that the compressor has failed and recommends replacing the whole system.
Now the contract takes over. The company may ask whether the failure is due to age or lack of maintenance, which can matter if the contract excludes poorly maintained equipment. It may offer to replace only the failed part. If it approves a replacement, the payment may be limited by a cap, and newer equipment may require changes to ductwork, electrical service, or refrigerant lines that the contract treats as extra. Each of those points can turn a covered claim into a partial one.
None of this means the claim will be denied. It means the owner should know the answers before the heat wave, not during it. Keeping maintenance receipts, photos of the equipment, and copies of every communication puts the owner in a much stronger position.
If things go wrong
If a company denies a claim you believe is covered, ask for the reason in writing and the specific contract language it relies on. Many disputes are resolved by escalating within the company. If that fails, you can file a complaint with your state attorney general or consumer protection office, and the FTC invites people who have had a bad experience with a home warranty to report it at ReportFraud.ftc.gov. Small claims court is another option for modest amounts.
Check the company's track record
A contract is only as good as the company behind it. The FTC suggests researching a company's reputation before buying. Search online for the company name along with words like complaint or review, as the FTC suggests, and check whether your state attorney general or consumer protection office has received complaints. Some states regulate home warranty companies, so your state insurance or consumer protection department may have information as well.
Three older home scenarios
An older house with recently replaced systems. If the roof, heating and cooling, and water heater are all fairly new, many of them may still be under manufacturer or installer warranties. The FTC notes that a home warranty may duplicate coverage you already have. Check the existing warranties first.
An older house with aging but working systems. This is where a plan is most tempting. It can be useful if the contract clearly covers those systems, the caps are realistic, and pre-existing condition rules are reasonable. Ask the company in writing whether your specific equipment, given its age, is covered.
An older house with known problems. If the inspection already found failing equipment or active issues, a warranty is unlikely to pay for them, because they existed before coverage began. Negotiate with the seller for repairs or a credit instead.
A seller paid warranty versus buying your own
When the seller pays for the first year, the decision is easier, because the cost to you is limited to service fees. It still makes sense to read the contract and learn the claims process so you can use it if needed.
Renewing in year two is a separate decision. Look back at your actual claims, how the company handled them, and whether the coverage matched your home's needs. If the plan paid for little or created delays, the renewal premium may serve you better in savings.
The alternative: self insuring with a repair fund
Instead of paying a warranty company, you can direct the same money into a dedicated repair fund. Fannie Mae's homeowner guidance suggests a rule of thumb of budgeting 1% to 4% of a home's value each year for maintenance, and notes that owners of homes more than 30 years old may want to lean toward the higher end.
As an illustrative example, an owner who saves $600 a year in premiums plus the $200 she would have spent on service fees builds an $800 cushion in the first year and $4,000 after five years, if nothing breaks. Unlike a warranty, that money covers anything, including the roof, has no caps, and stays with you if you never need it.
The tradeoff is risk. A fund that is still small can be overwhelmed by a major failure early on. For some owners, especially those with little savings, a warranty may smooth out that early risk while the fund grows. For others, the fund alone is the better plan.
Questions to ask before you sign
Bring a short list to any home warranty sales conversation. Which systems and appliances are covered, and which are excluded? What is the cap per item and per year? What is the service fee, and is it charged per visit or per claim? How does the company define a pre-existing condition? Are code upgrades, permits, and haul away included? Can I use my own contractor? How long do approvals usually take? Can I cancel, and is there a fee?
Ask for the answers in writing, and compare them to the contract itself, because the contract is what governs.
Practical steps for a buyer of an older home
Read the inspection report and list each major system with its approximate age. Find out which items still have manufacturer or installer warranties and gather that paperwork. Price repairs for the systems most likely to fail in the next few years.
Then compare that list to the plan. If the plan covers the systems you are most worried about, at caps that match realistic repair costs, it may be worth buying. If the key items are excluded or capped low, a repair fund is likely the stronger choice.
Whichever route you choose, keep maintenance records. They help with warranty claims, and they help you sell the house later.
A home warranty can be a useful supplement for an older home, but it is not a substitute for knowing your systems and saving for them. Read the contract as if every unlisted item will be your bill, because it probably will be.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0

Passionate about breaking down complex finance-related concepts into simple terms to help everyday people.

Comments (0)