

Psychology of Spending: Why We Buy What We Do Not Need
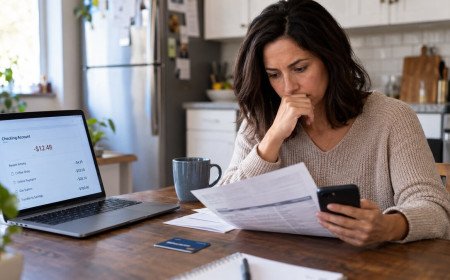
Most households do not blow their finances on a single reckless purchase. They leak money through dozens of small decisions that feel justified in the moment: a cart total that creeps up at checkout, a subscription that outlives its usefulness, a nicer version of something that already worked. The pattern is so common that it can feel like a personal failing. It is usually a predictable mix of brain shortcuts, social cues, and retail design. Understanding that mix is the first step toward spending that matches your values instead of your impulses. This article explains why we buy things we do not need, how marketers and apps amplify those tendencies, and which practical habits interrupt the cycle without requiring a joyless life. The goal is not perfection. It is fewer automatic purchases and more intentional ones.
Your Brain Prefers Now Over Later
Humans discount the future. A small pleasure today often beats a larger benefit next year in the mental math we actually use, even when a spreadsheet would disagree. That present bias shows up when you choose takeout over cooking after a hard day, or when you finance furniture you could have delayed three months. The future you who wanted a larger emergency fund is not standing at the register. Decision fatigue makes this worse. After a day of choices at work, the brain conserves effort. One-click checkout and saved cards remove the last bits of friction. Retailers know this. They design flows so the path of least resistance is to buy. Your job is not to become a robot. It is to reintroduce a little friction where your future finances matter most. Novelty also hooks attention. New packaging, limited drops, and “only three left” banners trigger scarcity responses that once helped with real shortages. Online, scarcity can be manufactured. Pause and ask whether the item would still matter next month if the banner disappeared.
Identity, Status, and the Purchases We Use as Signals
Spending is often a language. Clothes, cars, gadgets, and even grocery brands signal belonging to a group or distance from another. That is not automatically foolish, humans are social, but it becomes expensive when the audience is mostly strangers on a feed. Social media compresses comparison. You see curated peaks of other people’s consumption without their tradeoffs, debts, or parental help. Lifestyle inflation follows income for the same reason. A raise feels like permission to upgrade the baseline. The new baseline quickly feels normal, so happiness gains fade while the higher burn rate remains. If savings rates do not rise with income, you can earn more and still feel tight. Naming the upgrades you truly care about, and capping the rest, protects the raise. Children, partners, and friends shape norms too. If every gathering revolves around buying experiences you cannot comfortably afford, the pressure is social as much as financial. Honest conversations and cheaper rituals preserve relationships without pretending money is infinite.
Emotions at the Checkout
People shop to soothe boredom, anxiety, loneliness, or the need for a “win” after a rough week. The purchase delivers a short spike of control or anticipation. Then the package arrives and the feeling fades, sometimes replaced by guilt. That loop can look like a shopping problem when it is partly a stress-regulation problem. Budgeting alone rarely fixes it; you also need alternative resets that do not require a cart, walks, calls, hobbies, sleep. Retail therapy is not a moral crime in small doses. It becomes costly when it is the default coping tool and when it is invisible, digital stores open on the commute, late-night scrolling, package culture that treats delivery as entertainment. Track not only what you bought but what you felt in the ten minutes before you opened the app. Patterns appear quickly. Guilt after overspending can ironically trigger more spending if you try to “fix” your mood with another treat. Break that chain with a rule: after any unplanned purchase over a set amount, wait a week before another nonessential buy. Replace rumination with a concrete repair, such as moving the same amount to savings on payday.
How Stores and Apps Engineer Yes
Free shipping thresholds nudge you to add items you did not come for. Bundles reframe price. Buy-now-pay-later splits pain across time so the total hurts less in the moment. Personalized recommendations shrink the search for reasons to stop. None of these tools are illegal or always harmful. They simply optimize for conversion, not for your net worth. Subscription models turn a one-time decision into a recurring drain. Free trials convert because cancellation requires effort while renewal is automatic. Audit subscriptions monthly for the first quarter of a tightening plan, then quarterly forever. If you cannot name the last time you used a service, cancel and note whether you miss it within thirty days. Payment methods change behavior. Credit cards and stored profiles increase willingness to spend compared with cash for many people. That does not mean you must use cash for everything. It means high-temptation categories may deserve a debit card without online storage, prepaid caps, or a separate “fun money” account that cannot overdraft your rent.
Turning Insight Into Guardrails
Awareness without systems fades. Build defaults that assume future weakness. Remove saved cards from the sites that get you. Unsubscribe from marketing emails for brands that trigger you; keep a wishlist note instead of a full cart. Use browser blockers during known weak hours if late-night shopping is your pattern. Implement a waiting rule: twenty-four hours for small nonessentials, seven days for larger ones, thirty days for lifestyle upgrades like furniture or electronics upgrades when the old item still works. Wishlist the item with today’s date. Many urges expire. The ones that remain can be planned into the next payday without interest or guilt. Give every purchase a job. Write one sentence: “This replaces X,” “This enables Y goal,” or “This is entertainment within my fun budget.” If the sentence is “I felt stressed,” address stress first. If the sentence is “Everyone in my feed has one,” name the comparison and decide whether that audience is worth the cost.
Budgets That Respect Psychology
Strict budgets that ban all discretionary joy often fail and then rebound into splurges. Include a guilt-free spending category sized so you can use it. The point of a budget is allocation, not punishment. Automate savings and bills first so the leftover is truly available. That reverse-order planning uses present bias in your favor: the future gets paid before the app store does. Review weekly for ten minutes. Look at transactions with curiosity, not courtroom energy. Ask which buys aligned with your stated priorities, housing stability, debt payoff, experiences with people you love, health, learning, and which were noise. Adjust next week’s plan. Behavioral change is iterative. Couples should compare triggers openly. One partner may impulse-buy tools; the other may subscribe to beauty boxes. Joint visibility without humiliation works better than secret audits. Agree on a threshold that requires a quick text before purchase. Shared goals, like a trip fund with a progress meter, can compete with impulse urges more effectively than abstract “be good” advice.
When Spending Problems Need Broader Support
If spending feels compulsive, hides from family, or continues despite serious consequences, treat it as more than a budgeting tip sheet. Nonprofit credit counseling, a financial therapist, or other professional support may be appropriate. This article stays in education territory: patterns, incentives, and household systems. Serious distress deserves human help beyond a checklist. Debt from past impulse cycles needs a plan that combines behavior and math: stop adding new balances in trigger categories, pick a payoff method you will stick with, and rebuild a small cash buffer so the next surprise does not return you to the card. Tools matter; so does reducing the emotional load that sent you shopping.
Children, Gifts, and Holidays as Stress Tests
Gift culture amplifies spending psychology because refusal feels like a relationship risk. Set a household gift budget before the season starts, agree on experiences versus objects, and tell extended family early. Kids learn more from how you handle “everyone has it” pressure than from a lecture after an overspent holiday. Birthdays and back-to-school weeks deserve the same pre-commitment. Decide the number, not just the dollar cap: two outfits, one activity, one wish-list item. Limits stated as choices feel fairer than vague “we can’t.” For adults, suggest white-elephant or charity donations in lieu of piles of stuff when your circle is open to it.
Digital Carts, Returns, and the Illusion of Harmlessness
Easy returns lower the psychological cost of buying. You tell yourself you can always send it back, then inertia wins and the item stays. Count the time, packaging, and decision energy of returns as part of the price. A personal rule, no ordering without measuring space at home first, prevents closet overflow that later becomes donation clutter. Wishlist tools are healthier than carts. Moving an item to a wishlist satisfies the save-for-later urge without starting the shipping clock. Review wishlists on a scheduled day, not when you are tired. Delete anything that no longer excites you; that deletion is a financial win even though no money moved.
A Calmer Definition of Enough
Much unnecessary buying is a search for enough, enough comfort, status, preparedness, or novelty. Defining enough in writing sounds soft, yet it is one of the highest-leverage money exercises available. List what “comfortable and proud” looks like in housing, food, wardrobe, tech, and leisure. When a purchase does not move you toward that picture, it is a candidate for the waitlist or the no pile. Practice gratitude for what already works. That is not a slogan; it is a counterweight to novelty bias. Before replacing a phone, camera, or appliance, list three ways the current one still does the job. If it fails the list, replace it purposefully. If it passes, invest the upgrade money in the goals your future self keeps asking for. Spending psychology will not vanish because you read an article. Retailers will keep optimizing. Feeds will keep comparing. Your advantage is slower defaults, clearer priorities, and small frictions placed exactly where your past self stumbled. Buy what you need and what you truly value. Let the rest stay on the shelf, especially when the shelf is a glowing screen designed to say yes for you. Start with one change this week: a waiting rule, a subscription audit, or saved-card removal on your top trigger site. Measure results by fewer regret packages and steadier savings transfers, not by a personality makeover. Sustainable spending is a set of systems that respect how minds actually work. Keep the lesson portable: notice the trigger, delay the click, and fund the priorities you already named. That loop, repeated, reshapes spending more reliably than a single burst of frugality.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.










Comments (0)