

Zero-Based Budgeting for Beginners: How to Give Every Dollar a Job
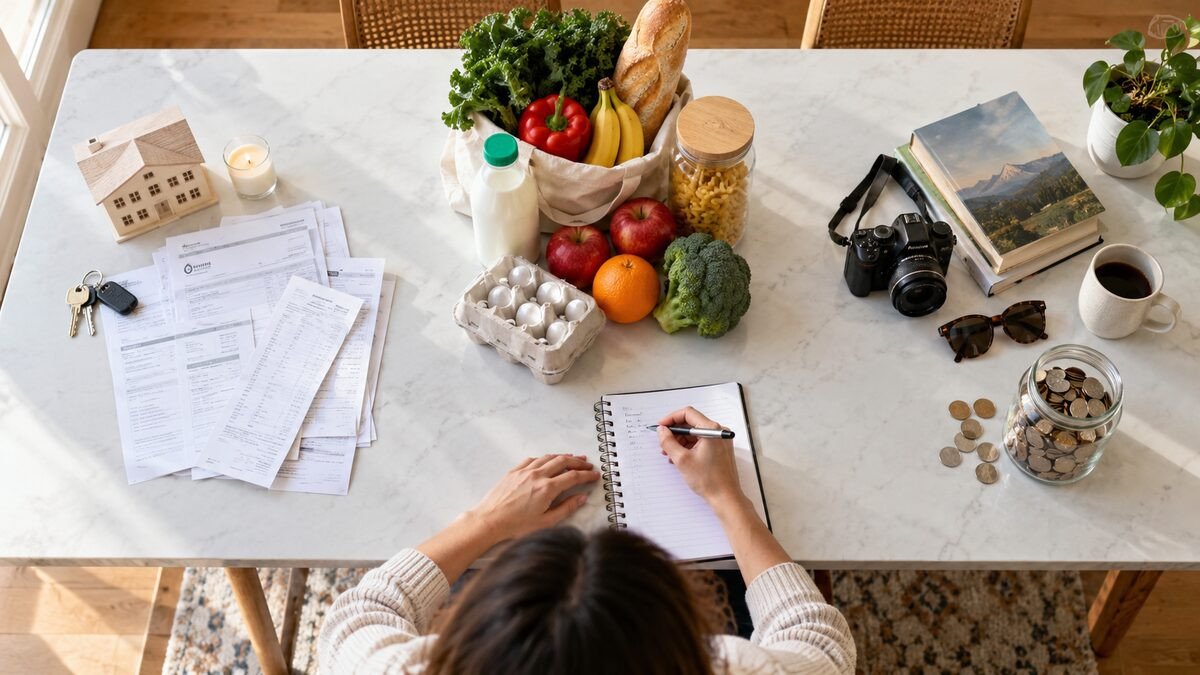
Zero-based budgeting has a reputation for being strict, but the core idea is simple: give every dollar of income a job before the month begins. Income minus assignments equals zero on paper. That does not mean your bank account is empty. It means wages, side income, and other deposits are fully allocated to needs, wants, savings, debt payments, and buffers so money cannot wander without a decision.
For beginners, this method is less about perfection and more about visibility. Many people feel broke at the end of the month without knowing where the money went. Zero-based budgeting forces an answer in advance. This guide shows how to start with realistic categories, handle irregular expenses, adjust mid-month, and stick with the system long enough to learn your real spending patterns.
What zero-based budgeting is and is not
Zero-based budgeting means your plan assigns 100 percent of expected income to categories until nothing is left unassigned. A dollar can be assigned to rent, groceries, transportation, streaming, sinking funds, extra debt payments, or next month's buffer. The identity of the job matters. Unassigned money is the usual leak.
It is not a vow to spend nothing fun. Fun can be a category. It is not a requirement to track every cent forever with military intensity. Many beginners track closely for two or three months to learn baselines, then simplify. It is also not the same as living on last month's income, though some households combine both ideas for extra stability.
Compared with a traditional percentage budget, zero-based planning is more detailed. Percentages can be a useful starting sketch. Zero-based budgeting then places actual dollars into actual jobs based on your bills and goals. The method shines when income is defined enough to plan, even if that income varies and you rebuild the plan each month.
Why beginners often succeed with this method
The first win is awareness. Writing assignments reveals whether the lifestyle fits the paycheck. If rent, insurance, minimum debt payments, and groceries already consume most income, the plan makes that math impossible to ignore. That clarity can feel uncomfortable and useful at the same time.
The second win is intentional tradeoffs. Want to increase dining out? The money has to come from another job, such as a slower savings transfer or a lower shopping category. Tradeoffs replace vague guilt with conscious choice. Over time, that reduces the sense that money disappears.
The third win is progress you can see. Categories for emergency fund, vacation, car repairs, and extra principal payments turn goals into funded lines rather than wishes. Even small assignments create momentum because the plan shows movement every month.
Step-by-step: build your first zero-based plan
Start with next month's expected take-home income, not gross pay. Include predictable side income only if it is reliable. If income varies, use a conservative baseline you are confident will arrive, and create a separate plan for surplus when a better month happens.
List fixed must-pay items first: rent or mortgage, utilities, insurance, minimum loan payments, childcare, basic groceries, required transportation, and medications. These are the skeleton of the plan. Use real bills and recent averages rather than optimistic guesses.
Next, add variable necessities with honest ranges: household supplies, gas, transit, modest personal care. Then assign money to priorities such as emergency savings, retirement contributions already deducted or still needed, extra debt payments, and sinking funds for known irregular costs.
Finally, assign money to lifestyle categories: dining, entertainment, hobbies, clothing, gifts. If the remaining income cannot cover the lifestyle you want, the plan is doing its job by surfacing the conflict early. Adjust before the month starts rather than inventing surprise money later.
When every dollar has a category and the leftover unassigned amount is zero, you have a complete plan. Keep it in a spreadsheet, a notebook, or a budgeting app. The tool is secondary to the habit of assigning before spending.
Sinking funds: the feature that makes zero-based budgets realistic
Annual and irregular expenses wreck monthly budgets that pretend every month is identical. Car registration, holiday gifts, back-to-school costs, pet vet visits, and insurance deductibles are predictable in kind even when dates vary. Sinking funds solve this by saving a little each month into named jobs.
Estimate the yearly cost, divide by twelve, and assign that monthly amount. When the expense arrives, you spend from the sinking fund category rather than raiding groceries or going backward on credit cards. Beginners should start with three to five sinking funds that historically hurt them most, not twenty perfect categories.
If cash is tight, underfund sinking funds temporarily rather than abandoning them. Five dollars a month toward car repairs is better than zero. Increase assignments when a debt is paid off or a subscription is canceled. Zero-based budgeting is iterative.
How to handle irregular income without quitting
Freelancers, commission earners, and gig workers can still use zero-based budgeting by planning from a floor. Determine the minimum monthly income you can reasonably expect, assign that amount completely, and keep a prioritized surplus list for months that exceed the floor. Surplus jobs might be taxes set-aside, emergency fund catch-up, and debt payoff in that order.
Another approach is to delay budgeting until income clears, then assign that exact deposit immediately. This works when bills can be timed after deposits. The key is speed: assign within a day so the money does not sit unlabelled in checking and invite accidental spending.
Mid-month reality checks without shame
A zero-based plan is a living document. If the water heater fails, you move money from lower-priority categories or from an emergency fund category to cover the repair. That is not failure. That is the system working. What matters is recording the move so you still know where you stand.
Review weekly for the first two months. Compare assigned amounts with actual spending. If groceries blow past the plan every week, raise the grocery assignment and cut a less essential category. A budget that ignores true grocery costs is a fiction. Accuracy beats aspirational underfunding.
Avoid the common beginner trap of dozens of tiny categories you will not maintain. Merge similar spending into broader buckets until habits stabilize. You can always split categories later when you need finer control.
Giving every dollar a job: practical category examples
Housing, utilities, groceries, transportation, insurance, minimum debt payments, phone and internet, household goods, medical, childcare, personal care, pets, subscriptions, dining out, entertainment, clothing, gifts and celebrations, emergency fund, retirement, extra debt payoff, vacation sinking fund, car maintenance sinking fund, and next-month buffer are enough for most beginners. Customize names so they match your life.
Include a miscellaneous category with a small amount for true unknowns. Then protect it from becoming a junk drawer for avoidable spending. If miscellaneous is always empty by week two, either life is volatile or the category is absorbing unplanned lifestyle purchases that deserve their own line.
Common mistakes and how to avoid them
Using gross income instead of take-home pay inflates the plan and guarantees frustration. Planning with last month's unusual overtime as if it were permanent does the same. Base the plan on dependable net income.
Forgetting annual expenses creates fake success for eleven months and a crisis in month twelve. Sinking funds are not optional decoration. They are how zero-based budgeting survives contact with real calendars.
Being too harsh on lifestyle categories can cause binge spending. A sustainable plan includes modest fun you will actually follow. Likewise, being too loose on high-interest debt while funding luxury categories may feel pleasant and still leave you stuck. Align assignments with written priorities.
Abandoning the plan after one messy month is another common exit. The first month is diagnostic. The second month is adjustment. The third month is often where the method starts feeling natural. Give the learning curve room.
How zero-based budgeting pairs with banking automation
Once categories are stable, automate what you can: rent, minimum debt payments, and transfers to savings sinking funds on payday. Leave flexible categories for manual decisions. Automation should express the plan, not replace it. If you automate first and plan never, you may still overdraw or shuffle shortfalls.
Some people keep category balances in one checking account and track on paper or in an app. Others use multiple savings sub-accounts labeled for each sinking fund. Choose the lowest-friction structure you will maintain. Perfect infrastructure with abandoned tracking loses to a simple spreadsheet you open weekly.
A thirty-day starter challenge
Week one: gather net income figures and the last 60 days of spending. Draft fixed categories. Week two: add variables, sinking funds, and lifestyle lines until the assignment total equals income. Week three: live the plan and record every move between categories. Week four: revise next month's plan using what you learned, then automate two or three high-priority transfers.
At the end of thirty days, judge the system by clarity, not by whether you followed it perfectly. If you can explain where next month's paycheck will go before it arrives, you have already gained the main beginner skill zero-based budgeting teaches.
Couples and families using one zero-based plan
Households with more than one decision maker need a shared plan and clear ownership of categories. Decide who updates the spreadsheet, who pays which bills, and how personal spending money is assigned so autonomy does not look like secrecy. A short monthly meeting to reset next month's assignments prevents unilateral changes that break trust.
If one partner is a detailed tracker and the other is not, simplify the shared categories and let the detail-oriented partner handle sinking fund math. The less interested partner still needs visibility into totals and upcoming large expenses. The plan fails when only one person understands it.
Debt payoff inside a zero-based framework
Minimum payments belong in the must-pay section. Extra payments become intentional assignments after essentials and a basic emergency buffer. Some beginners choose avalanche ordering by interest rate. Others choose snowball ordering by smallest balance for motivation. Either approach works better when the extra payment amount is written as a category rather than leftover hope.
When a debt is eliminated, immediately reassign that payment's dollars to the next priority before lifestyle inflation absorbs them. That reassignment step is where zero-based budgeting creates lasting change instead of a temporary squeeze.
Measuring success beyond perfect adherence
Useful metrics include fewer surprise shortfalls, a rising emergency fund category, on-time bills, and less end-of-month anxiety. Perfect category accuracy every week is a weaker success measure. If the plan helps you make earlier tradeoffs and fund goals, it is working even when you move money mid-month.
Keep the philosophy, flex the format
You can later simplify categories, switch apps, or adopt a hybrid with percentage targets. Keep the philosophy: money gets a job on purpose. That mindset is what reduces leaks, funds goals, and replaces end-of-month confusion with earlier, calmer decisions.
Zero-based budgeting for beginners is not about becoming a spreadsheet personality overnight. It is about making income and priorities meet on one page before the month spends itself. Give every dollar a job, revise without drama, and let the plan teach you what your life actually costs. That education is the real return.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Shula is an experienced content writer with a strong background in developing engaging and informative articles. She has written across diverse topics, including personal finance, lifestyle, food, and travel. With a clear and adaptable writing style, Shula brings value by making complex subjects accessible to a broad audience.










Comments (0)