Financial Infidelity: How to Talk About Hidden Debt or Spending With Your Partner
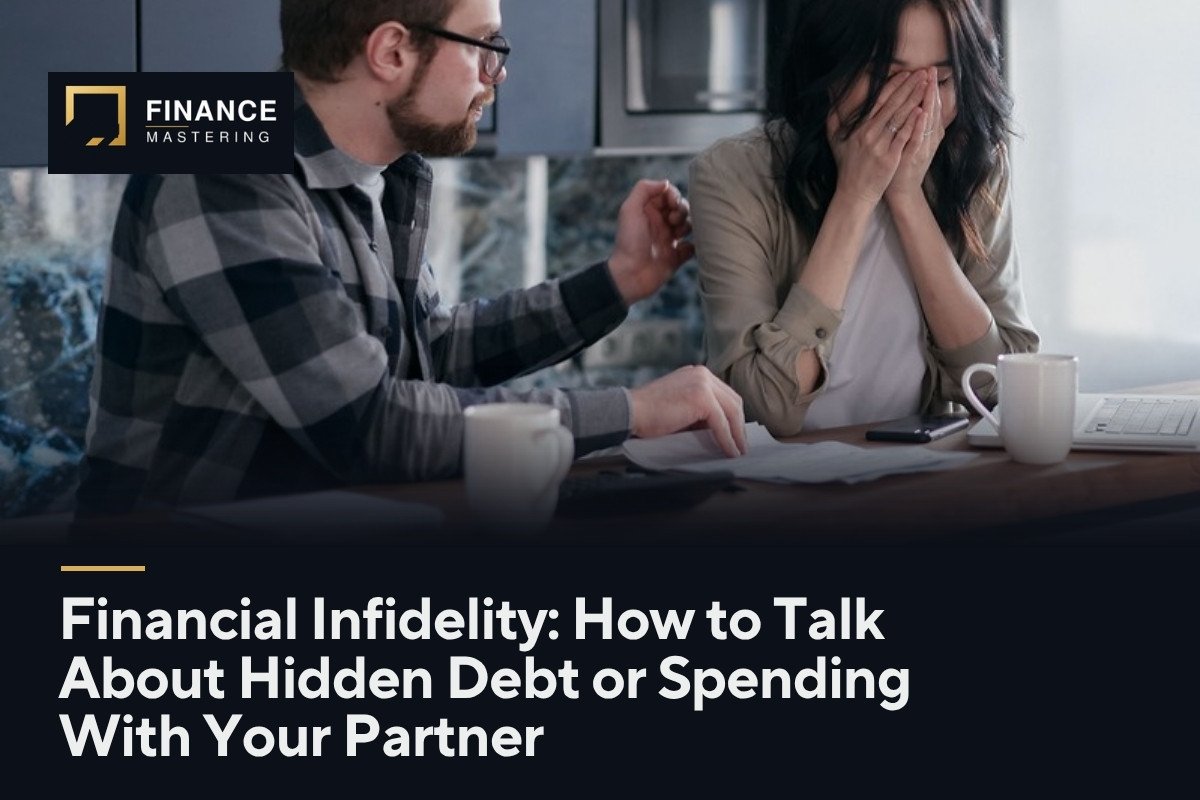
The statement arrives for a credit card Jordan did not know existed, with a balance of $6,800 and a minimum payment due in nine days. Alex, who opened the card during a year of job stress, has been paying it from a side account and hoping to clear it before it surfaced. Jordan's first questions are financial: whose debt is it, what else is hidden, and can the household still pay its rent? Underneath them is a harder one: how do you talk about money with a partner who has been hiding part of it?
Financial infidelity is a useful label for secret accounts, hidden debt, concealed purchases, or lying about income, savings, or credit. It is not a legal diagnosis and it does not tell you who owes a creditor. This article is general education, not legal, tax, or therapy advice. Safety comes first. If there is coercion, intimidation, blocked access to money, or fear of retaliation, involve a trusted professional, advocate, or attorney before holding a joint financial meeting. A conversation plan is not a substitute for protection.
Slow the first conversation down
Discovery often creates an urge to demand every answer in one night. You need facts, but an exhausted interrogation can produce fresh concealment, especially if shame drove the secrecy. Set a short first meeting with one purpose: establish the scope, stop new damage, and schedule the full review. Say, in ordinary words, that hidden debt affects both people's choices even when only one person spent the money, and that the next step is records rather than guesses. If either person is too angry to hear numbers, agree on a date within days, not someday, and write down what will be gathered before then.
Begin with a narrow disclosure list. Ask for every account in each name and in both names: credit cards, personal loans, buy-now-pay-later balances, payday or auto title loans, tax debts, medical bills in collections, overdrafts, margin or brokerage debts, and loans from family or employers. Ask also about hidden spending channels that may not be debts, such as a secret savings account funded by diverting joint income, cash advances, or a stored card on a shopping account. The point is not to rank betrayals. It is to prevent a second discovery after you have built a plan on incomplete numbers.
Put a temporary fence around new borrowing while you talk. That can mean pausing use of joint cards, removing stored payment details, lowering cash access, or agreeing that neither person opens or closes credit, moves large sums, or makes a major purchase until the review is done. Changing passwords, freezing credit, or removing an authorized user can have legal and practical consequences depending on whose account it is. Do not lock a partner out of money they legally need for food, medicine, work, or legal advice. If control of money is itself the dispute, a neutral professional or attorney should help design the interim steps.
Separate the relationship debt from the creditor debt
A household can experience a debt as shared while a creditor sees only one liable person, or the reverse. The Consumer Financial Protection Bureau explains that on a joint credit card account, each joint account holder is generally responsible for the full balance, including charges made by the other holder. An authorized user, by contrast, generally is not liable for the account debt, though the primary cardholder is responsible for charges the authorized user makes. State law, the account contract, divorce decrees, and community property rules can change how responsibility is allocated, so this distinction is a starting map rather than a verdict.
That means three questions must be asked separately for every balance. Whose name signed or co-signed the obligation? Is it secured by a home, car, or deposit that a creditor can pursue? And how will the household choose to pay it, regardless of what a creditor could enforce? A divorce judgment between spouses does not by itself remove a name from a creditor contract, as the CFPB notes in its divorce and debt guidance. One person may be ordered to pay while both remain exposed to the lender if the account is joint. Refinancing, closing, or a written release from the creditor are different events from a private promise.
Pull the records together rather than trading screenshots. Each adult can request their own credit reports through the federally authorized AnnualCreditReport.com system referenced by the Federal Trade Commission, and can share the reports at the meeting. Read for accounts you do not recognize, balances in collection, and recent inquiries that suggest an application you did not discuss. Check bank and card statements for transfers to unfamiliar accounts, cash advance fees, interest charges, and minimum payments leaving through autopay. If you find an account that may be identity theft, fraud, or opened in your name without consent, document it and contact the issuer promptly. Couples issues and fraud can look similar on a statement, but they require different calls.
Also check the quiet obligations. A tax installment agreement, a wage garnishment, a child support arrears balance, a 401(k) loan, or a debt owed to a relative may not appear the way a card balance does. Ask directly about lawsuits, collection letters being sent to another address, and any account where mail has been redirected. If a partner says everything is now disclosed, ask them to say so plainly after the reports and statements are open, and set a date to recheck in 30 days. Trust is rebuilt by verified consistency, not by a single dramatic confession.
Hold the full review like a business meeting with a heart
Choose a private time when neither person is leaving for work, caring for children alone, intoxicated, or already in a fight. Bring a notebook, the account list, statements, credit reports, and a calculator. Agree that either person can call a pause, but a pause ends with a time to resume. Start by naming the shared goal before naming blame: keeping housing stable, stopping interest and fees, protecting children and credit, and deciding what must change for money to be open again. Those goals can coexist with anger. They give the anger somewhere useful to go.
Work account by account. For each debt, record the creditor, whose name is liable, balance, annual percentage rate or other cost, minimum payment, due date, collateral, and whether payments are current. For each hidden purchase or transfer, record what it was only to the extent needed to understand ongoing obligations and whether an asset exists that could be sold. A household budget review is not a cross-examination about every meal or gift. It is a search for recurring costs, undisclosed commitments, and money still leaving the account.
Then total the minimum payments and compare them with take-home pay and essential bills. The CFPB's budgeting and debt materials consistently point households toward listing income, bills, and debts before choosing a payoff order. If minimums plus housing, utilities, food, transport, insurance, and medicine exceed reliable income, say so plainly. This is no longer only a trust conversation. It is a solvency conversation, and it may require calling creditors about hardship options, speaking with a nonprofit credit counseling agency certified through a reputable referral source, or consulting a bankruptcy attorney for information before missed payments narrow the choices. Seeking advice is not agreeing to a plan.
Decide what happens to the secret account during repayment. Options can include leaving it open with both people able to view it, closing it to new purchases while paying it down, removing online access that enabled concealment, or setting alerts for both phones. The right control depends on legal ownership and safety. Transparency tools should be mutual and written: shared calendar reminders for due dates, a monthly statement review, alerts above an agreed amount, and a rule that new credit requires a conversation first. A rule imposed on only one person in secret recreates the original problem with a different author.
Talk about the cause without making it the payment plan
After the numbers are visible, ask what the secrecy protected. Common answers include shame about job loss, fear of a partner's anger, a gambling or shopping compulsion, substance use, an affair, helping a relative against a partner's wishes, or a belief that the debt would be gone before discovery. The cause does not excuse the lie, and understanding it does not require the other person to comfort the person who concealed it. It tells you what support or boundary must accompany repayment. A budget cannot treat a compulsion. A payment plan cannot repair a pattern of financial control. Match the remedy to the behavior.
Use statements that describe impact and the decision ahead. You might say that learning about the debt from a statement changed whether you feel able to sign a lease, plan a child, or trust a future budget, and that you need verified openness to make shared commitments again. Avoid diagnosing your partner or declaring what they intended if you do not know. Ask what they hid, when, why they chose secrecy, whether anyone else knows or is owed money, and what they have already done to stop it. Write the answers down. Memory changes after an emotional talk, and written notes let later meetings begin from facts rather than competing recollections.
Some couples can repair this with structured openness and counseling. Some need a therapist who works with couples and money, a financial therapist, a mediator, or separate attorneys, especially where large debts, a business, a home, or children are involved. If one partner refuses full disclosure, continues opening accounts, intercepts statements, or insists that questions are the real offense, treat that behavior as information. You can still protect yourself by gathering your own reports, keeping copies of joint obligations, documenting agreements, and getting legal advice about accounts in your name. Love and liability are different systems, and you are allowed to attend to both.
Protect children from becoming messengers or witnesses. They may need a calm explanation if routines change, but they do not need balances, blame, or instructions to keep secrets from the other parent. Keep the financial meetings adult, scheduled, and bounded. If spending must fall, explain the family change in terms of a plan rather than a punishment. Hidden debt already taught the household what secrecy feels like. The recovery should model the opposite.
Rebuild with a short agreement and a recheck date
End the review with a written 30-day agreement. It should list every disclosed debt, the payment to be made, who will make it, the date new spending controls begin, when statements will be reviewed together, and what counts as a breach that requires outside help. Include ordinary money as well as the crisis account: how income will be deposited, how joint bills will be paid, what personal spending amount each adult can use without consultation, and a threshold above which both people agree before buying. Personal allowances are not a loophole for new secrecy. They are a pressure valve that makes honesty livable.
Recheck the credit reports and account list on the date promised. Look for new inquiries, rising balances, cash advances, and accounts that were omitted. Celebrate boring evidence: statements opened on time, payments made as agreed, and a hard purchase discussed before it happened. Repair will be slower than discovery, and that is not failure. A single apology is an event. Six months of visible, verifiable openness is a pattern.
Jordan and Alex cannot settle $6,800 and a broken expectation in one evening, but they can leave the first talk with every known account listed, no new borrowing, and a date to review statements together. Start there if this is your household. Facts first, liability second, causes third, and a written recheck to prove that the secrecy has actually ended.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Shula is an experienced content writer with a strong background in developing engaging and informative articles. She has written across diverse topics, including personal finance, lifestyle, food, and travel. With a clear and adaptable writing style, Shula brings value by making complex subjects accessible to a broad audience.
Comments (0)