Living on One Income: How Single-Earner Households Build a Budget That Works
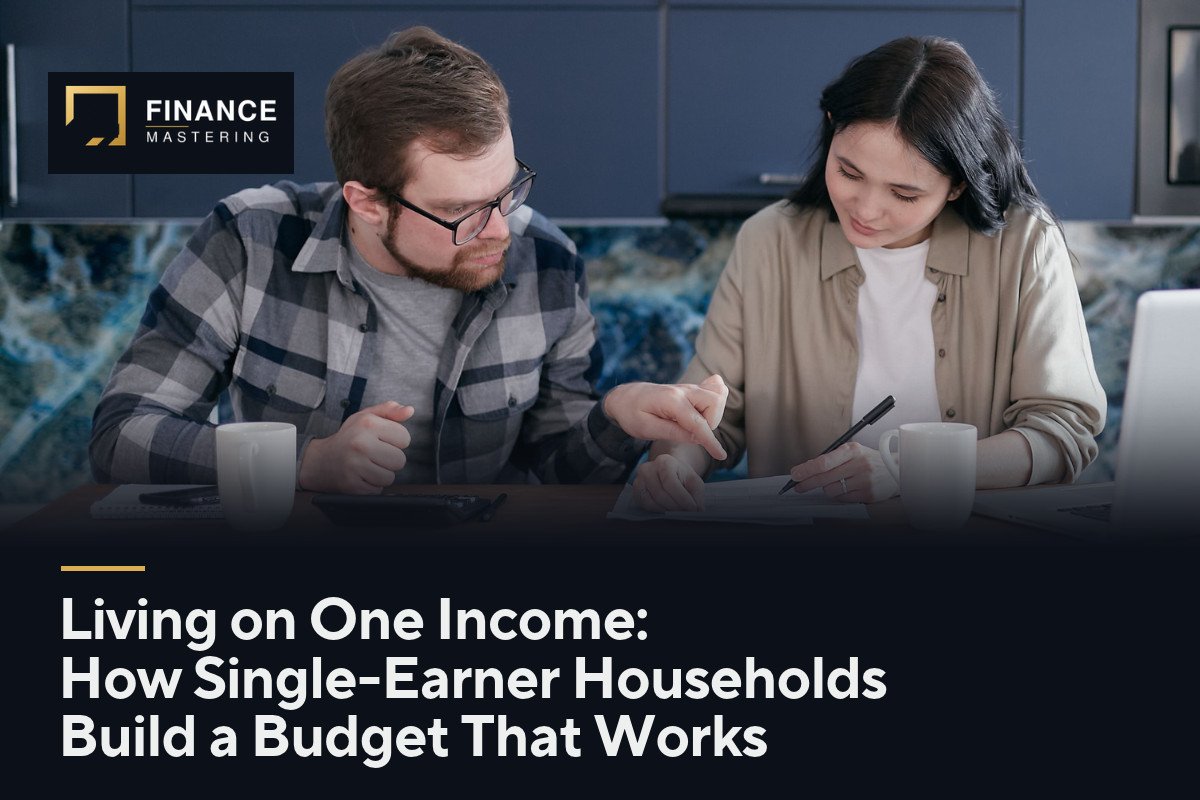
Marcus Rivera's paycheck from a hospital supply company in Columbus, Ohio, lands every other Friday at about $2,750 after taxes, health insurance, and his 401(k) deduction. Until last spring, his wife, Elena, brought home roughly the same amount as a dental office manager. Then their second child arrived, the quote for two kids in full-time day care came in near $2,400 a month, and Elena decided to stay home for a few years. The figures here are examples, but the problem is real for many American families: the household is the same size, the mortgage did not shrink, and there is now one paycheck doing the work of two.
A single-earner budget is not simply a two-income budget with the numbers cut in half. The structure has to change, because the household loses its built-in backup. This guide covers how to set it up so it holds steady, from the order of the bills to the protections that matter more when one person earns all the money.
Start from the paycheck you actually receive
Plans built on gross salary tend to fail in the first month. Use net pay, the amount that reaches checking after taxes, insurance premiums, and retirement deductions. In the example, Marcus earns $96,000 a year and brings home about $5,500 in a typical month, with two "extra" paychecks a year because he is paid every two weeks.
Those two extra checks are useful. A biweekly worker gets 26 paychecks, so building the monthly budget on two paychecks leaves two full checks a year unassigned. Many single-income families send those straight to the emergency fund or to annual bills such as car insurance and property tax that do not come out of escrow.
Next, check whether your withholding still fits. When a couple filing jointly goes from two incomes to one, the household often moves into a lower tax bracket, and withholding set for two earners may now be too high. The IRS Tax Withholding Estimator can help you update Form W-4 with your employer. For reference, the IRS lists the 2026 standard deduction for married couples filing jointly at $32,200, rising to $33,200 for tax year 2027.
Rank the bills before you trim them
With one income, the order you pay things in matters as much as the total. A simple ranking keeps the essentials safe if a month runs short:
First, housing, utilities, food, and transportation to work. Second, insurance premiums that protect the earner and the household. Third, minimum payments on debts. Fourth, savings for irregular bills. Fifth, everything else, including retirement savings above any employer match, subscriptions, dining out, and gifts.
In the Riveras' example, the fixed core looks like this: a $1,750 mortgage payment including escrow, $380 in utilities and phone, $950 for groceries and household supplies, $420 for a $300 car payment plus gas for both cars, and $160 in life and disability premiums. That is $3,660, leaving about $1,840 of the $5,500 for minimum debt payments, savings, and flexible spending.
The Consumer Financial Protection Bureau describes the debt-to-income ratio as all monthly debt payments divided by gross monthly income, and notes that different lenders set different limits. It is worth calculating at home even if you are not applying for a loan. On Marcus's $8,000 gross monthly pay, the $1,750 mortgage payment plus the $300 car payment come to about 26 percent. A family with one income generally has less room to absorb a new debt, so keeping that figure from creeping up is one of the simplest guardrails available.
Decide what the at-home work is worth
Here is where single-earner budgets often go wrong in the other direction. The parent at home is doing work the family would otherwise pay for, and that work has a price tag even if no one sends a bill.
For the Riveras, the clearest number is the day care quote, about $2,400 a month in this example. Elena's previous take-home pay was about $5,500 a month, but after child care, commuting, a second car's wear and tear, and work lunches, the net gain from her job was far smaller than her salary suggested. Running that math honestly helps a couple make the decision without guilt in either direction and gives them a number to revisit when the children start school.
It also changes how you think about insurance. If something happened to the parent at home, the earner would likely need to buy child care, and possibly more, while still working full time. That cost belongs in the life insurance conversation for both spouses, not just the one with the paycheck.
Protect the one income from every angle
When two people earn, a job loss or illness for one of them is painful but survivable. When one person earns, the same event can stop the household's cash flow completely. That raises the priority of four protections.
An emergency fund sized for one income. Base it on the essential expenses from your ranked list, not your full spending. In the example, the Riveras chose six months of their $3,660 core, about $22,000, as a long-term target, and they are building it with the two extra paychecks and a fixed monthly transfer. Choose the number of months based on how stable your job is, how quickly you could find another, and whether the at-home spouse could return to work.
Disability coverage for the earner. An earner's ability to work is the household's main asset. Check what group long-term disability coverage pays at work, what percentage of salary it replaces, and when benefits begin. If the employer plan leaves a gap against your core expenses, consider individual coverage.
Life insurance for both spouses. Coverage on the earner replaces income. Coverage on the at-home parent pays for the care and household help the family would need to hire.
Health insurance continuity. If the spouse who left work had family coverage through that job, make sure everyone is enrolled in the remaining plan. HealthCare.gov explains that losing job-based coverage can qualify a household for a Special Enrollment Period, generally with 60 days to pick a Marketplace plan, and that COBRA may let a family continue an employer plan for a limited time. Missing the window can leave a gap that is expensive to fix.
Keep the at-home spouse on the financial map
Stepping away from paid work affects more than the monthly budget. It can affect that spouse's retirement, Social Security record, and credit history, and each one is easier to protect now than to repair later.
Social Security credits. The Social Security Administration requires 40 credits for a worker to qualify for retirement benefits on their own record. In 2026, SSA says one credit is earned for every $1,890 in covered earnings, with a maximum of four credits a year at $7,560. SSA has set the 2027 amount at $1,970 per credit. A spouse who already has 40 credits keeps them. A spouse with fewer credits who later does part-time or freelance work can keep adding to the record.
Spousal benefits. SSA's family benefits page notes that a spouse may receive up to half of the worker's benefit amount, depending on age and other factors. That is a meaningful safety net, but it is tied to the marriage and to the worker's record, so it is not a substitute for the at-home spouse's own savings.
A spousal IRA. The IRS allows a spouse with little or no compensation to contribute to an IRA when the couple files jointly, as long as the couple's combined contributions do not exceed the taxable compensation reported on the joint return. For 2026, the IRS limit is $7,500 per person, or $8,600 for someone age 50 or older. Contributions for a tax year can generally be made until the return's due date, not counting extensions. Even modest monthly contributions keep the at-home spouse's retirement account growing.
Credit in their own name. Keep at least one credit card or account in the at-home spouse's name or as a joint account holder, and make sure that person can see every account, password, and bill. Shared visibility protects both people.
Watch for tax changes that come with one paycheck
Some tax benefits depend on both spouses working. The child and dependent care credit is the most common example. IRS Publication 503 says that to claim it, you and your spouse, if filing jointly, generally must both have earned income during the year, with exceptions for a spouse who was a full-time student or was not able to care for themselves. A family that claimed the credit while both parents worked may lose it in the first full year with one income. Plan for a slightly smaller refund rather than counting on last year's number.
Employer benefits deserve a fresh look too. If the earner's workplace offers a dependent care account, a health savings account, or extra life insurance, open enrollment is the time to change elections to match the new household. Contributions you no longer need, such as to a dependent care account with no eligible expenses, can be redirected to the emergency fund.
Build a monthly rhythm, not a rigid plan
A single-income budget works best when it is boring and automatic. Schedule transfers for the day after payday: one to savings, one to a separate account for irregular bills, and one to any retirement contributions. Pay the core bills from checking and leave flexible spending in a set weekly amount, so a big Monday at the grocery store does not crowd out Thursday.
Once a month, the couple should look at the numbers together for about 30 minutes. Check the checking balance against the next two weeks of bills, the progress on the emergency fund, and anything unusual coming up, such as a school trip or a car registration. Equal say in the budget matters more when only one person brings home a paycheck, because it keeps the arrangement feeling like a partnership rather than an allowance.
Expect to revisit the plan at predictable moments: when a child starts kindergarten, when the earner gets a raise, when the mortgage or a car loan is paid off, and when the at-home spouse is thinking about going back to work. Each one changes the math, sometimes in your favor.
When the numbers do not close
If the ranked list leaves no room for savings after a few months of honest tracking, the gap is structural. The largest lines usually offer the best fixes: a refinance or a move to lower housing costs, replacing a car payment with a paid-off vehicle, or lowering insurance costs by raising deductibles once the emergency fund can cover them. Part-time, seasonal, or remote work for the at-home spouse can also close a gap and add Social Security credits at the same time.
One income can support a stable household when the bills are ranked, the earner is protected, and the at-home spouse stays visible in every account. Set the system up once, check it monthly, and let the two extra paychecks do the heavy lifting.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
James Johnson has 10+ years in fintech. He holds an MBA and an MS in Information Technology, and writes about how AI and personal finance actually meet for everyday investors.
Comments (0)