

HSA vs. FSA: Which Tax-Advantaged Health Account Should You Use?
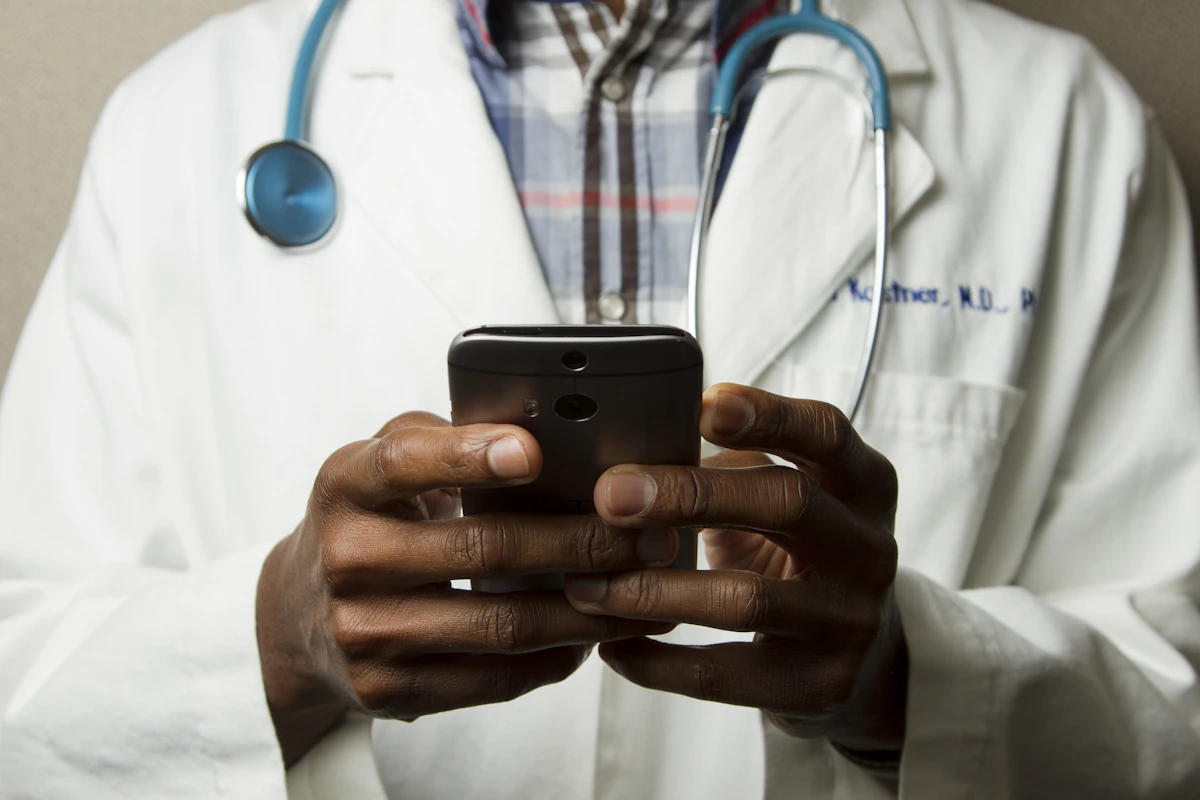
Health savings accounts and flexible spending accounts can both reduce the cost of eligible health expenses, but they work in very different ways. Choosing between an HSA and an FSA is not simply a matter of picking the account with the larger tax benefit. Eligibility, employer rules, expected medical spending, cash flow, and your willingness to plan ahead all matter.
This guide explains the practical differences so you can make a more informed benefits decision. It is educational and does not replace advice from a tax professional or your employer's benefits administrator.
The short answer
An HSA is usually the more flexible long-term account because the money belongs to you, rolls over without an annual expiration date, and may be invested when the provider allows it. However, you can contribute only if you are enrolled in an HSA-eligible high-deductible health plan and meet the other eligibility rules.
A health care FSA is tied to an employer benefits plan. It can be useful when you want predictable, tax-advantaged money for near-term expenses, especially because the full annual election is generally available early in the plan year. The tradeoff is that unused funds may be forfeited, subject to any carryover or grace-period feature offered by the employer.
How an HSA works
An HSA is an individually owned account available to eligible people covered by a qualifying high-deductible health plan. Contributions may come from you, your employer, or both. The combined amount must stay within the applicable annual limit.
Payroll contributions are often the most tax-efficient route because they may avoid federal income tax and payroll taxes. Contributions made outside payroll may still qualify for an income-tax deduction, but the payroll-tax treatment can differ. State tax treatment is not uniform, so residents should check their own state rules.
You can use HSA money tax-free for qualified medical expenses. If you keep the account invested instead, unused money can continue rolling over from year to year. The account stays with you when you change employers, change insurers, or retire.
How a health care FSA works
A health care FSA is established through an employer. During benefits enrollment, you elect how much of your pay to direct into the account for the coming plan year. Contributions normally reduce taxable wages, and qualified reimbursements are tax-free.
A useful FSA feature is uniform coverage. In many plans, the entire annual election is available for eligible claims near the beginning of the plan year even though the money is deducted gradually from later paychecks. Someone who schedules an expensive eligible procedure in January may therefore have access to the elected amount before making every payroll contribution.
The limitation is portability. An FSA generally remains connected to the employer plan, and unused money may not follow you after a job change. Plan documents determine claim deadlines, substantiation requirements, carryover amounts, and any grace period.
Ownership is the biggest dividing line
HSA money belongs to the account holder. The balance does not disappear merely because a calendar year ends. That makes an HSA useful for both current bills and future health costs.
FSA money belongs within the employer's plan structure. The familiar use-it-or-lose-it rule still matters, although some employers offer a limited carryover or a grace period. A plan cannot necessarily offer every relief feature at once, and the available amount may change from year to year. Never assume last year's rule still applies without reviewing the new benefits materials.
Eligibility can decide the question before preference does
You cannot choose an HSA solely because you like its rollover feature. You must have qualifying health coverage and must not have disqualifying additional coverage. Enrollment in Medicare, certain other health plans, or another person's general-purpose health FSA can affect eligibility.
A general-purpose health FSA normally reimburses a broad range of qualified medical expenses and can make an employee ineligible to contribute to an HSA. Some employers instead offer a limited-purpose FSA that covers dental and vision expenses while preserving HSA eligibility. A post-deductible FSA may also be structured to coordinate with an HSA.
Because coverage combinations can be complicated, confirm eligibility with the plan administrator before contributing. An excess HSA contribution can create tax complications that are easier to prevent than correct.
Comparing the tax advantages
Both accounts can reduce taxable income when funded correctly. Both can also provide tax-free reimbursement for qualified expenses. The HSA adds a potential third benefit: investment growth can remain tax-free when later withdrawn for qualified medical costs.
That triple-tax structure makes an HSA unusually powerful, but it should not distract from immediate needs. Investing every dollar while carrying high-interest debt or lacking money for the health plan deductible can create avoidable financial stress. The account works best as part of a complete cash-flow plan.
An FSA has no comparable long-term investment role, but it may deliver a meaningful current-year tax benefit. If a household already knows it will spend money on prescriptions, therapy, eligible dental work, glasses, or other qualified care, routing those dollars through an FSA may lower the effective cost.
Which account is better for predictable expenses?
An FSA can be attractive when expenses are predictable and the annual election can be estimated conservatively. Review the prior year, then separate recurring expenses from one-time events. Recurring prescriptions, regular therapy visits, contact lenses, orthodontic payments, and planned procedures may be easier to forecast.
Avoid treating the election as a savings goal. An overly aggressive estimate can leave money at risk near the claim deadline. Build the election from expenses you reasonably expect, then check whether the employer provides a carryover or grace period.
An HSA also works well for predictable expenses, but spending is optional. You may pay an eligible bill from the account today, or you may pay with other funds and leave the HSA invested. If you plan to reimburse yourself later, retain organized records showing that the expense was qualified, incurred after the HSA was established, and not reimbursed elsewhere.
Which account is better for long-term saving?
The HSA is generally stronger for long-term accumulation because balances roll over and may be invested. Some people build a cash reserve inside the HSA equal to their deductible or expected near-term costs, then invest amounts above that reserve.
Investment options, minimum cash requirements, administrative fees, and fund expenses vary by provider. An HSA should not automatically be invested without considering when the money may be needed. Funds required for care next month should not be exposed to stock-market volatility.
After age 65, nonmedical HSA withdrawals generally avoid the additional tax that applies to younger account holders, although ordinary income tax may still apply. Qualified medical withdrawals remain tax-free. This gives the account added flexibility in retirement, but using it for health expenses normally preserves the strongest tax benefit.
Cash-flow differences can affect the decision
An FSA can help with a large early-year bill because the annual elected amount is generally available upfront. An HSA usually makes only the current account balance available. If you elect to contribute throughout the year, the full annual amount may not be present in January.
That distinction matters for families with planned care early in the year. The FSA may provide faster reimbursement, while the HSA may require temporary use of other savings or a payment plan until contributions accumulate.
Also consider the underlying insurance plan. A high-deductible plan may have lower premiums, but the deductible, coinsurance, prescription coverage, provider network, and out-of-pocket maximum can outweigh the account tax benefit. Compare the entire health plan, not just the HSA contribution.
Qualified expenses and documentation
Eligible expenses often include deductibles, copayments, prescriptions, dental care, vision care, and many over-the-counter products. Insurance premiums are more restricted and require careful attention to the specific rules.
Keep itemized receipts, explanations of benefits, and proof of payment. A card swipe does not by itself prove that an expense qualifies. FSA administrators commonly request substantiation, and HSA owners are responsible for supporting tax-free withdrawals if questioned.
Do not seek reimbursement twice. An expense reimbursed by insurance, an FSA, an HSA, or another source cannot also be claimed again from a second account. The same expense generally cannot be used for both tax-free reimbursement and a medical-expense deduction.
Can a household use both?
Some households can combine an HSA with a limited-purpose FSA. The limited-purpose account may pay eligible dental and vision costs, allowing the HSA balance to remain available for other medical expenses or long-term growth.
A dependent care FSA is a different benefit and does not function like a health FSA. It covers qualifying dependent-care expenses under separate rules and generally does not interfere with HSA eligibility in the same way as a general-purpose health FSA.
Married couples should review both employers' elections together. One spouse's general-purpose FSA may cover the other spouse and affect HSA contribution eligibility even when the HSA is offered through a different employer.
A practical decision process
- Confirm whether your health plan is HSA-eligible and whether any other coverage affects eligibility.
- Compare premiums, deductibles, employer contributions, coinsurance, networks, and out-of-pocket maximums.
- Estimate recurring qualified expenses using recent bills and planned care.
- Check the FSA carryover, grace-period, claim-deadline, and termination rules.
- Review HSA fees, investment options, and any required cash balance.
- Choose a contribution that supports real expenses without weakening your emergency fund.
Common mistakes to avoid
The first mistake is choosing a high-deductible plan only to gain HSA access. A plan with unsuitable coverage or unaffordable cost sharing can erase the benefit. The second is overfunding an FSA based on optimistic guesses rather than documented expenses.
Another mistake is investing the entire HSA balance while lacking cash for the deductible. Long-term growth is valuable, but health expenses do not wait for favorable market conditions. Finally, failing to keep receipts can undermine delayed HSA reimbursement or create trouble when an FSA requests documentation.
Bottom line
Choose an HSA when you are eligible, the underlying health plan fits your needs, and you value portability and long-term flexibility. Choose a health care FSA when it is offered, your expenses are predictable, and you can make a conservative election under the employer's deadlines. If a limited-purpose FSA is available, it may complement an HSA rather than compete with it.
The best choice is the one that fits both your health coverage and your cash flow. Review the plan documents every enrollment season because limits and employer features can change.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.









Comments (0)