

529 Plans Explained: Tax Benefits, Eligible Expenses, and Key Rules
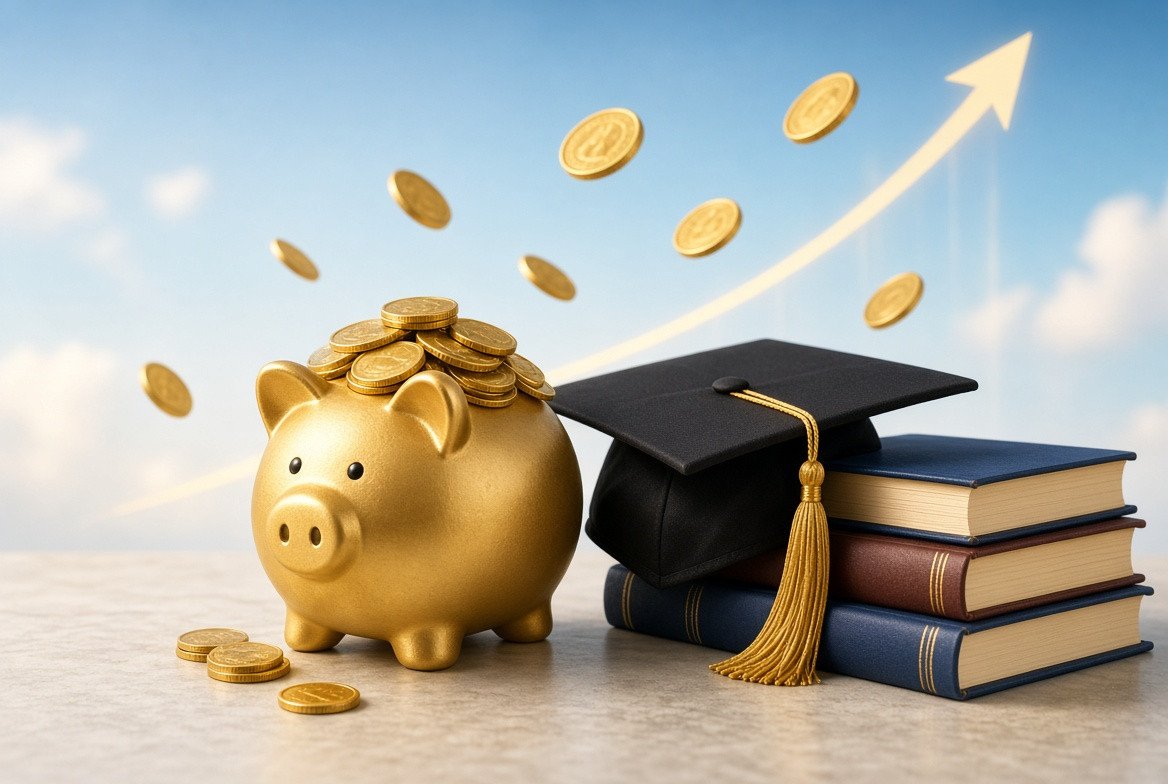
A 529 plan is a tax-advantaged account designed to help families save for education. Federal law calls it a qualified tuition program, and states or state agencies establish the plans. Contributions are not deductible on the federal return, but investment earnings can grow without current federal tax and qualified withdrawals can be federal-income-tax-free.
The tax treatment is valuable, but the account has rules. Qualified expenses, state tax benefits, beneficiary changes, financial-aid treatment, and withdrawal timing can all affect the result. IRS Publication 970 and Topic 313 provide the federal framework, while each state plan supplies its own program details.
Two basic types of 529 plans
Education savings plans let the account owner choose from an investment menu and use qualified withdrawals for eligible expenses. Prepaid tuition plans generally allow families to purchase future tuition benefits under program-specific rules. Most families discussing a “529” mean the investment-based education savings account.
The account owner controls the money and names a beneficiary. Plans commonly permit changing the beneficiary to another qualifying family member, which can help if the original student does not use the full balance.
Federal tax advantages
Contributions use after-tax money. Earnings are not included in federal taxable income while they remain in the plan, and qualified distributions are generally excluded from federal income when used for eligible expenses.
Some states offer deductions, credits, matching programs, or other benefits for contributions. The benefit may depend on using the home-state plan, and a prior state tax benefit may be recaptured after certain rollovers or nonqualified withdrawals.
Expenses that may qualify
Qualified higher-education costs can include tuition, required fees, books, supplies, and equipment. Computers, internet access, and certain room-and-board costs may qualify when statutory conditions are met. Apprenticeship expenses and limited student-loan repayments may also qualify under federal rules.
Federal law also permits limited K–12 tuition withdrawals, subject to the annual federal cap and state treatment. Rules evolve, so confirm the current federal and state requirements before withdrawing.
Avoid double-dipping tax benefits
The same expense generally cannot support both a tax-free 529 withdrawal and an education credit such as the American Opportunity Tax Credit. Scholarships, employer assistance, refunds, and other tax-free educational help can reduce the expenses available for 529 treatment.
Coordinate withdrawals with the school’s billing calendar and keep receipts, account statements, enrollment information, and proof of payment.
What if the student does not need all the money?
Options may include changing the beneficiary, saving the account for future education, using it for another eligible expense, or taking a nonqualified withdrawal. Nonqualified withdrawals generally make the earnings portion taxable and may trigger an additional federal tax.
Current federal law also permits certain limited direct rollovers from long-held 529 accounts to the beneficiary’s Roth IRA when multiple conditions are satisfied. Lifetime, annual, account-age, and contribution-history rules apply, so this is not an automatic escape hatch.
Investment risk and age-based options
529 education savings accounts are investments, so balances can rise or fall. Age-based portfolios typically become more conservative as college approaches, while static portfolios maintain their allocation until the owner changes it.
Review expenses, investment choices, performance benchmarks, and how quickly the portfolio reduces risk. Money needed next semester should not carry the same market exposure as money intended for a newborn’s future education.
Financial aid and ownership
Financial-aid treatment can depend on who owns the account and which aid methodology applies. Rules for federal aid have changed over time, and private institutions may use additional calculations.
Do not choose an owner or beneficiary structure based on an outdated rule of thumb. Check the current aid application instructions and the plan documents.
The bottom line
A 529 can be a powerful education-savings tool when the tax advantages, investment allocation, and withdrawal records are managed together. Compare state benefits and fees, match risk to the student’s timeline, and coordinate distributions with other education tax benefits.
This article is for general educational purposes and is not individualized financial, tax, or investment advice.
Choosing a plan: home-state benefits versus lower costs
You are generally not required to use your home state’s 529 education-savings plan. Start by checking whether your state offers a deduction, credit, matching contribution or creditor protection that depends on using its own plan. Then compare that value with investment expenses, administrative fees and fund quality elsewhere.
A tax deduction is not equal to the amount contributed; its value depends on the applicable state tax rate and the program’s rules. A high-fee plan can gradually consume an upfront benefit, while a strong home-state incentive may outweigh a modest fee difference.
Gift-tax and contribution considerations
529 plans often accept contributions far above the annual federal gift-tax exclusion, but a large contribution can require gift-tax reporting. Federal law provides a special election that may allow a contribution to be treated as made over five years, subject to detailed rules and adjustments for other gifts.
Plan maximums, state rules and family circumstances still apply. A contribution that is allowed by the plan is not automatically free from estate- or gift-tax considerations, so unusually large deposits deserve professional tax guidance.
Coordinate withdrawals within the same tax year
Match qualified withdrawals with eligible expenses paid during the same calendar year. A spring tuition bill, fall housing charge and December reimbursement can create recordkeeping problems if distributions and payments cross tax years without a clear plan.
Decide whether the plan should pay the school directly, reimburse the account owner or reimburse the beneficiary. Keep the tuition statement, invoices, receipts and proof of payment together with the 529 distribution record.
Scholarships do not automatically make the account useless
When a beneficiary receives a scholarship, the account owner may have several choices: preserve the funds for future education, change the beneficiary, use the balance for another permitted expense or withdraw an amount connected to the scholarship. Federal exceptions may remove the additional tax in certain situations, but the earnings portion can still be taxable.
The timing and amount of the scholarship-related distribution matter. Confirm current rules instead of assuming the entire account can be withdrawn tax-free.
Review the account as college approaches
A portfolio suitable for a young child may be too volatile when tuition is due next semester. Review the allocation at least annually and more frequently as withdrawals approach. Age-based portfolios automate part of this transition, but their glide paths and underlying costs differ.
Also update successor-owner instructions and beneficiary information. Because the owner controls distributions, a clear succession plan can prevent administrative confusion if the original owner dies or becomes unable to manage the account.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Shula is an experienced content writer with a strong background in developing engaging and informative articles. She has written across diverse topics, including personal finance, lifestyle, food, and travel. With a clear and adaptable writing style, Shula brings value by making complex subjects accessible to a broad audience.










Comments (0)