

Sector ETFs Explained: Benefits, Risks, and Hidden Concentration
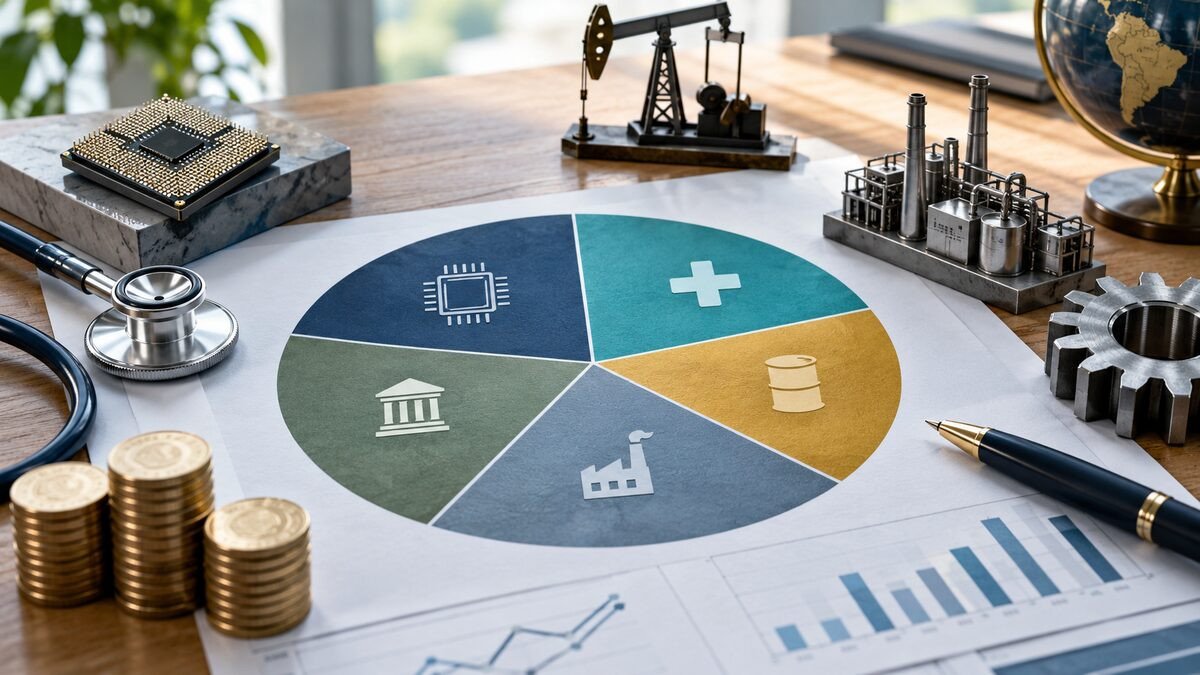
Sector exchange-traded funds let investors concentrate on one part of the economy, such as technology, health care, energy, financial services, or consumer staples. They can be useful tools, but they are often misunderstood. Buying a sector ETF is not the same as buying a broadly diversified stock-market fund with a slightly different label.
A sector fund makes an active decision about where returns will come from. That decision can increase upside when the selected industry leads the market, but it can also increase losses, volatility, and the risk of underperforming for years.
What a sector ETF actually owns
A sector ETF holds a basket of companies classified within a particular economic segment. The fund may track a well-known index or a custom benchmark created by an index provider. Its holdings and weights follow the benchmark methodology rather than a manager's daily opinion.
The word sector sounds broad, but the portfolio may be dominated by a handful of large companies. A technology ETF can place substantial weight in several mega-cap firms. An energy fund may depend heavily on oil and gas producers. A financial fund can be shaped by large banks, insurers, or payment companies depending on its classification rules.
Before buying, review the fund's holdings, concentration, index rules, expense ratio, assets, trading volume, and bid-ask spread. The fund name alone does not reveal how it behaves.
Sector ETFs are different from broad-market funds
A total-market or broad large-cap index fund owns companies across many areas of the economy. Weakness in one sector may be offset by strength elsewhere. The portfolio also adjusts naturally as industries grow, shrink, and change in market value.
A sector ETF removes much of that diversification. It intentionally ties more of the result to one set of business drivers. Interest rates may dominate financial stocks, commodity prices may dominate energy companies, regulation may affect health care, and consumer spending may shape discretionary businesses.
This does not make sector funds automatically bad. It makes them specialized. A specialized tool needs a defined role, position limit, and exit or rebalancing rule.
The main potential benefits
Sector ETFs provide instant access to a group of companies without requiring investors to select individual winners. Someone who believes an industry has favorable long-term conditions can spread company-specific risk across multiple holdings.
They can also be used to adjust an existing portfolio. An investor whose broad fund has less exposure to a desired sector than intended may add a small allocation. Others use sector funds to express a tactical view, manage tax lots more easily than a collection of individual stocks, or avoid the research burden of analyzing every company.
The ETF structure also offers intraday trading and transparent holdings in many cases. Costs can be lower than those of some actively managed specialty funds, although a sector ETF is generally more expensive than a plain broad-market index fund.
Concentration can hide behind a long holdings list
A fund may own dozens of securities and still be concentrated. The important issue is not only how many names appear in the portfolio. It is how the money is distributed among them.
Market-cap-weighted funds assign larger weights to companies with larger market values. If a few firms become enormous, they can drive a large share of the sector fund's movement. Fifty holdings do not provide the diversification investors might expect when the top five represent a major portion of assets.
Equal-weighted funds reduce dependence on the largest names, but they introduce different risks. They allocate more to smaller companies, trade more frequently to rebalance, and may behave differently from the headline sector index. Neither approach is universally superior.
Overlap is another source of hidden risk
Investors often own a broad index fund and then add a sector ETF without checking overlap. Because the broad fund already owns many of the same companies, the new purchase may double or triple exposure to familiar holdings.
Suppose a large technology company is already one of the biggest positions in an S&P 500 fund. Adding a market-cap-weighted technology ETF may not create meaningful new diversification. It may simply increase dependence on that company and its closest peers.
Use a fund-overlap tool or compare the top holdings manually. Look at the combined portfolio rather than evaluating every fund in isolation.
Sector classification is not always intuitive
Index providers place companies into categories according to formal classification systems. A business that consumers view as a technology company may be classified under communication services or consumer discretionary. Payment networks, real-estate platforms, and online retailers can also appear in sectors that surprise casual investors.
Two funds with similar names may track different classifications and hold noticeably different portfolios. Read the index description and top holdings to understand what exposure you are actually purchasing.
Performance chasing is a major behavioral risk
Sector funds often attract attention after a strong run. Headlines highlight the industry's recent gains, fund flows increase, and investors buy because the trend feels obvious. Unfortunately, a high past return can also mean valuations and expectations are already elevated.
Leadership rotates. A sector can outperform for several years and then lag when interest rates, earnings growth, regulation, commodity prices, or investor sentiment change. Buying after a surge and selling after a decline turns a specialized fund into a mechanism for chasing performance.
Before investing, write down the reason for the allocation and what evidence would invalidate it. If the only explanation is that the sector has recently gone up, the decision may lack a durable foundation.
Valuation still matters
A promising industry can be a poor investment when prices assume flawless growth. Revenue expansion does not guarantee strong shareholder returns if investors paid too much or if competition reduces profit margins.
Review valuation measures in context. Price-to-earnings ratios, cash-flow multiples, profitability, expected growth, and balance-sheet strength vary by sector. Banks should not be evaluated exactly like software companies, and regulated utilities should not be compared directly with early-stage biotechnology firms.
Valuation cannot reliably identify a short-term top, but it helps investors understand how much optimism is embedded in the price.
Business-cycle sensitivity differs by sector
Consumer discretionary, industrial, financial, and materials companies may be sensitive to economic growth. Utilities, health care, and consumer staples are often described as defensive because demand may be steadier, but they can still decline and face sector-specific problems.
Interest rates affect sectors differently. Higher rates can pressure highly valued growth stocks and rate-sensitive real estate, while parts of the financial industry may benefit or suffer depending on lending margins, deposit costs, and credit losses. Energy companies can respond more to commodity supply and demand than to the domestic economy alone.
A sector allocation is therefore a view not only on companies but also on economic conditions and how markets have priced them.
Costs extend beyond the expense ratio
The expense ratio is the annual fund cost deducted from assets, but it is not the only trading cost. Investors may also face a bid-ask spread, brokerage limitations, taxes, and the behavioral cost of frequent switching.
Funds with limited assets or trading volume can have wider spreads, especially during volatile markets. Use limit orders when appropriate and avoid assuming that a small quoted share price means the fund is inexpensive.
Turnover inside the fund and your own holding period can affect tax efficiency in a taxable account. Review distributions and consult a tax professional for individual circumstances.
How much is too much?
There is no universal allocation, but sector exposure should be evaluated relative to the entire portfolio. A five-percent position can create more than five percent of the risk when it overlaps heavily with other holdings or contains volatile companies.
A common framework is to keep a diversified core and place specialized ideas in a smaller satellite allocation. The core provides broad exposure, while the satellite has a written maximum. This prevents one conviction from quietly becoming the portfolio's dominant risk.
Stress-test the position. Consider how the portfolio would feel if the sector fell 30 percent while the broad market declined much less. If that outcome would trigger panic selling, the position may be too large.
Rebalancing provides discipline
A sector that outperforms can grow far beyond its intended weight. Rebalancing trims the position and redirects money toward underweight areas. A sector that falls may be restored to target only if the original investment case remains intact.
Choose a rule before emotions take over. You might review allocations quarterly or annually, or rebalance when a holding moves beyond a predetermined range. Tax consequences and transaction costs should be considered in taxable accounts.
Questions to ask before buying
- What index does the ETF track, and how are companies selected and weighted?
- How much of the fund is held in its five or ten largest positions?
- How much overlap exists with funds already in the portfolio?
- What economic or business factors could hurt the sector?
- Is the allocation strategic, tactical, or simply driven by recent performance?
- What is the maximum position size and the rebalancing rule?
- Are the expense ratio, spread, liquidity, and tax effects acceptable?
When a sector ETF may be unnecessary
Investors who want long-term market exposure with minimal maintenance may not need sector funds. A broad-market portfolio already allows successful industries to increase in weight as their market values rise.
A sector ETF may also be unnecessary when the investor cannot explain the thesis, does not intend to monitor the allocation, or already owns substantial employer stock in the same industry. Employment income and investment exposure can become dangerously connected during an industry downturn.
Bottom line
Sector ETFs offer convenient, diversified access within a specific industry, but they do not provide broad diversification across the economy. Their greatest risks are concentration, overlap, performance chasing, and an allocation that grows beyond its intended role.
Start with the total portfolio. Understand the benchmark, top holdings, valuation, costs, and economic drivers. If the fund has a clear purpose, keep the position controlled and rebalance with a written rule. A sector ETF should support a financial plan, not replace one.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.









Comments (0)