The Cost of Caregiving: How to Budget When You Help an Aging Parent
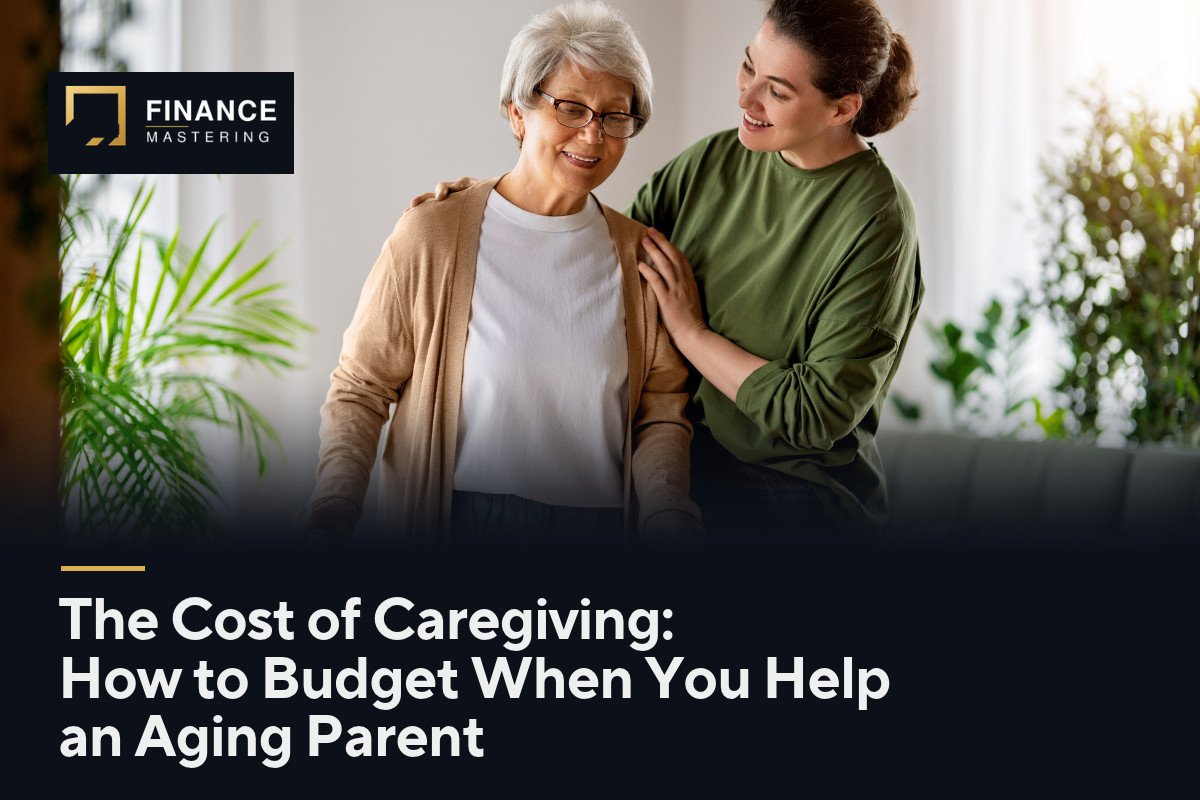
Renee Carter did not decide to become a caregiver. It happened one errand at a time. Her mother, who lives alone in Greenville, South Carolina, stopped driving after a fall, so Renee started making the two-hour trip from Charlotte every other weekend. Then came a shower grab bar, a medical alert subscription, a few afternoons of paid home help, and two unpaid days off when her mother came home from the hospital. When Renee finally added it up in October, she had spent more than $6,000 since spring, and none of it was in her budget.
That pattern is common. Caregiving costs rarely arrive as one big bill. They arrive as gas, copays, groceries, hours you did not work, and small purchases that each seem too minor to plan for. The fix is not to spend less on someone you love. It is to give those costs a name, a line in your budget, and a limit you choose on purpose. Renee's numbers here are an illustrative example, not a benchmark.
Start With a Cost Inventory, Not a Budget
Before you can budget for care, you need to know what it already costs. Pull the last three months of bank and card statements and mark every expense connected to your parent. Most families find their spending falls into a handful of buckets.
Direct care: paid home aides, adult day programs, respite stays, or a share of assisted living.
Medical extras: copays, prescriptions, hearing aids, dental work, mobility equipment, and supplies that insurance does not fully cover.
Household support: groceries, utilities, meal delivery, lawn care, or a portion of your parent's rent or property tax.
Travel: mileage, gas, tolls, flights, parking at the hospital, and the occasional hotel night.
Home changes: grab bars, ramps, railings, better lighting, a raised toilet seat, or a stair lift.
Your own lost time: unpaid leave, reduced hours, skipped overtime, or a freelance contract you turned down.
Write a monthly average next to each bucket, and keep irregular costs separate. A $40 weekly grocery run is a steady cost. A $1,200 bathroom modification is a one-time cost. Mixing them makes your monthly number look either scarier or smaller than it really is.
Count Your Parent's Money Before Your Own
The next step is a quieter one: figure out what your parent can pay for themselves. List their monthly income, such as Social Security, a pension, or annuity payments, and their fixed bills. The difference is what is available for care before anyone else contributes.
Many adult children skip this step because talking about a parent's money feels awkward. But covering costs your parent could comfortably afford can drain your savings while their own income sits unused. In Renee's example, her mother had about $400 a month left after her own bills, which could cover most of the groceries and medications Renee had been quietly paying for.
Ask gently, and frame it as planning rather than control. The goal is a shared picture of what care costs and who can pay which part.
The Line Item Most Families Leave Out
The cost that often matters most never shows up on a statement: the income you give up. If you are paid hourly, each missed shift has a clear price. If you are salaried, the cost may show up later as a smaller raise, a stalled promotion, or a decision to step back to part-time.
Federal law offers some protection, but not pay. Under the Family and Medical Leave Act, eligible employees of covered employers can take up to 12 workweeks of unpaid, job-protected leave in a 12-month period to care for a parent with a serious health condition. The Labor Department notes that leave can be taken intermittently or on a reduced schedule when medically necessary, which is often how caregiving actually works. Eligibility generally requires at least 12 months with the employer, 1,250 hours of work in the prior 12 months, and a worksite where the employer has at least 50 employees within 75 miles. The federal definition of parent does not include parents-in-law. Some states offer paid family leave or broader protections, so check your state labor department.
For budgeting, treat lost income as a real expense. In Renee's example, two unpaid days at $240 a day cost her $480, more than a month of gas for her trips. When you see that number, paying for a few hours of home help so you can keep working may look less like a luxury and more like a bargain.
What Your Parent's Coverage Will Not Pay
Many families assume Medicare will step in once care becomes regular. It usually does not. Medicare.gov is direct about it: Medicare does not pay for long-term care, which includes help with everyday personal tasks such as dressing, bathing, and using the bathroom, whether at home or in a nursing home. Medicare Supplement Insurance, or Medigap, does not cover it either. Medicare does cover some skilled care after a qualifying hospital stay, but that is different from ongoing custodial help.
The main public program that pays for long-term care is Medicaid, for people who meet their state's eligibility rules. Some people also have private long-term care insurance. If your parent has a policy, find it now and read the elimination period and daily benefit, because those details determine how long your family pays before benefits start.
This gap is why caregiving budgets tend to grow over time. The early years may be mostly travel and small purchases. Later years can involve paid care for many hours a week. Planning for both stages keeps you from being surprised by the shift.
Build the Budget in Three Layers
Once you have your inventory, turn it into a plan with three layers.
The first layer is the monthly baseline. Add up the steady costs you expect to keep paying, such as groceries, medications, gas, and a set number of paid care hours. In this example, Renee's baseline came to about $650 a month. That amount gets its own line in her budget, just like her car payment.
The second layer is a caregiving reserve. Set aside a separate savings bucket for one-time and surprise costs: the next equipment purchase, a hospital stay that requires you to travel, or a month when your parent needs extra help. Renee chose to add $150 a month to a separate high-yield savings account labeled for her mother. Keeping it separate from her own emergency fund protects both.
The third layer is your ceiling. Decide in advance how much you can contribute each month without cutting your own retirement saving or emergency fund. This is the hardest number to set, and the most important. A ceiling is not a lack of love; it is what keeps your help sustainable for years instead of months.
Review all three layers every quarter, or whenever your parent's health changes. Caregiving budgets are rarely stable for long.
Tax Rules That Might Help, and Their Limits
A few federal tax rules can offset part of the cost, but each one has specific tests. Treat this as a starting point for a conversation with a tax professional, not a plan.
Claiming your parent as a dependent. A parent can be your qualifying relative even if they do not live with you, but you generally must provide more than half of their total support for the year, and their gross income must be below a limit. For 2026, that limit is $5,300, according to IRS Revenue Procedure 2025-32. Gross income for this test includes taxable Social Security benefits, but not the nontaxable portion. If your parent qualifies, you may be able to claim the Credit for Other Dependents, worth up to $500, with a phaseout that begins above $200,000 of adjusted gross income, or $400,000 for joint filers.
Sharing support with siblings. If no one person provides more than half, but together you do, IRS Publication 501 explains a multiple support agreement. One sibling who provides more than 10% can claim the parent if the others sign statements agreeing not to, and the claim is documented with Form 2120.
Medical expenses. If you itemize, the IRS says you can deduct medical expenses you pay for a parent who is your dependent, but only the portion of total medical expenses that exceeds 7.5% of your adjusted gross income. Some home modifications made for medical reasons, such as ramps, widened doorways, and grab bars, can count as medical expenses under IRS Publication 502.
Care that lets you work. If your parent lives with you for more than half the year and cannot care for themselves, paid care that allows you to work may qualify for the Child and Dependent Care Credit. Beginning in tax year 2026, the IRS says the credit ranges from 20% to 50% of qualifying expenses, depending on income, and the expense limit stays at $3,000 for one qualifying person. The exclusion for employer dependent care benefits, including a dependent care FSA, rises to $7,500 for 2026, or $3,750 for married people filing separately.
Split the Load Before It Splits the Family
If you have siblings, the money conversation is easier when it starts with your inventory rather than with feelings. Share the actual monthly baseline and the reserve target, then decide who covers what. Contributions do not have to be equal in dollars. A sibling who lives nearby may give time, while one across the country contributes cash for paid help.
Write the arrangement down, even informally, and revisit it when costs change. Clear expectations prevent the quiet resentment that builds when one person absorbs costs no one else sees.
Protect Your Own Future While You Help
It is easy to pause retirement contributions to cover a parent's needs. Be careful. Skipping your workplace match or draining your emergency fund can create a second financial problem down the road, possibly for your own children.
A practical rule: keep contributing at least enough to get any employer match, keep your emergency fund separate from the caregiving reserve, and treat any amount above your ceiling as a signal to look for outside help rather than a reason to borrow.
Free and Low-Cost Help Worth Checking
Outside help may be closer than you think. The National Family Caregiver Support Program, run through the federal Administration for Community Living and local aging agencies, funds services for adult family caregivers of people 60 and older, and of people of any age with Alzheimer's disease or related disorders. Services include information, help getting access to services, counseling and training, respite care, and limited supplemental services.
Your local Area Agency on Aging can tell you what is available in your parent's county, from meal programs to adult day care to short respite breaks. Even a few hours a week of respite can make a full-time job and a caregiving role possible at the same time.
Caregiving is easier to sustain when its cost is visible and capped. Price it honestly, give it a budget line, set aside a reserve, and ask for help before the ceiling is tested.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.

Comments (0)