

The Pay-Yourself-First Budget: A Simpler Way to Save Without Tracking Every Dollar
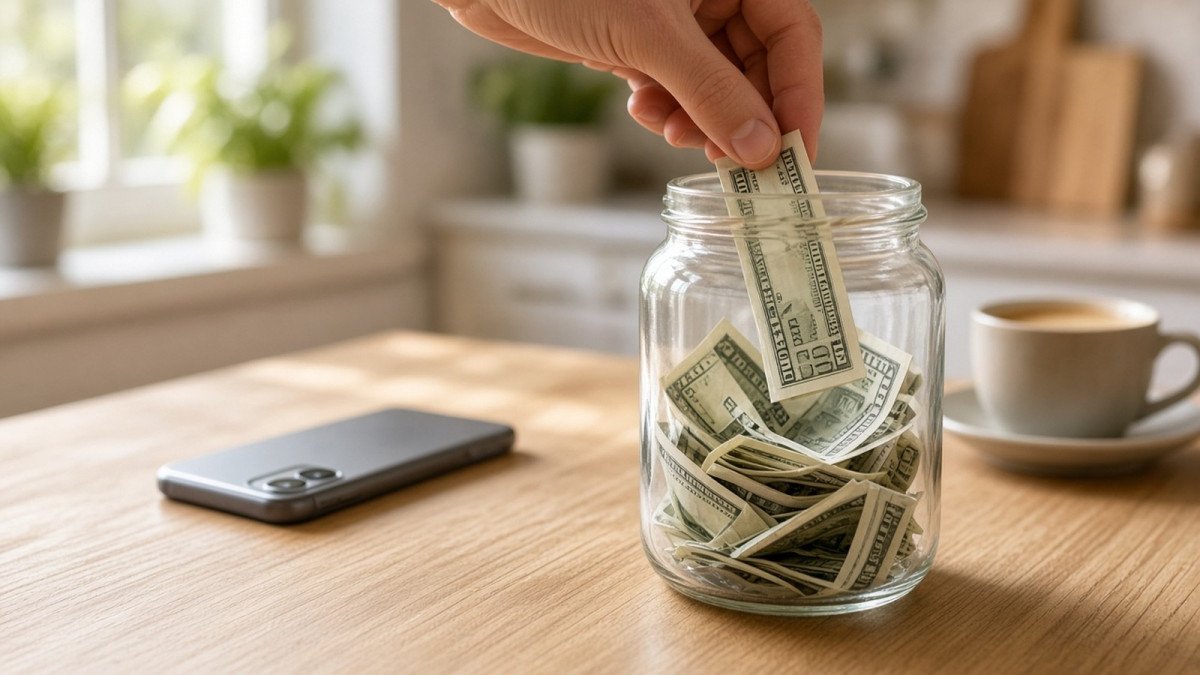
Traditional budgeting asks you to track every purchase, assign every dollar a category, and review your spending regularly. For some people that structure is exactly what they need. For many others, it becomes a chore that lasts a few weeks before the spreadsheet goes stale and the app notifications get ignored. The pay-yourself-first budget takes a different approach. Instead of monitoring everything you spend, you decide how much to save, move that money out of reach as soon as you are paid, and then spend what is left without guilt or detailed tracking.
This guide explains how the pay-yourself-first method works, how to pick a savings rate, where the money should go, how to set it up so it runs automatically, and when the approach needs extra guardrails. The examples use illustrative numbers. It is general education rather than personalized financial advice, so adjust the ideas to your own income, debts, and goals.
What pay yourself first means
The phrase comes from an old principle in personal finance: treat savings as the first bill you pay each month rather than whatever happens to be left over at the end. Most people save in reverse. They pay their bills, spend on daily life, and plan to save the remainder. The trouble is that spending tends to expand to fill the money available, so the remainder is often small or nothing at all.
Paying yourself first flips the order. On payday, a fixed amount or percentage of your income goes directly to savings and investment accounts before you have a chance to spend it. Your fixed bills come next. Whatever remains is yours to spend on groceries, entertainment, dining out, and everything else, and you do not need to log each purchase as long as you stay within that remaining balance.
The method works because it relies on structure rather than willpower. You make the important decision once, when you set up the automatic transfers, instead of making dozens of small decisions every week.
Why it can work better than tracking every dollar
Detailed budgets fail for predictable reasons. They take time, they require constant attention, and a single bad week can make people feel they have blown the whole plan. Pay yourself first reduces the number of things you have to get right. If your savings goal is met automatically and your bills are covered, the precise split between coffee and takeout matters much less.
It also protects your priorities. Because savings happen first, an expensive month affects your spending money rather than your long-term goals. You might have less for restaurants after an unexpected car repair, but your retirement contribution still went in on schedule.
There is a behavioral advantage as well. Money that never lands in your everyday checking account is easier to leave alone. Many people find that they adjust their spending to what they see available without feeling deprived, especially when the savings increase gradually.
Choosing your savings rate
The first decision is how much to set aside. A commonly cited target is saving around 15% of gross income for retirement, including any employer match, plus additional savings for emergencies and shorter-term goals. That is a useful benchmark, not a requirement. If you are carrying high-interest debt or living on a tight income, starting lower and building up is far better than not starting at all.
Here is an illustrative example. Suppose your take-home pay is $5,000 a month and you decide to pay yourself first with 15% of it, or $750. You might split that into $250 for an emergency fund, $300 for a Roth IRA, and $200 for a vacation fund. If your fixed bills, including rent, utilities, insurance, minimum debt payments, and subscriptions, total $2,900, you have $1,350 left for flexible spending each month, or roughly $310 a week.
If $750 feels impossible, try 5% and raise it by one or two percentage points every few months or each time you get a raise. Small increases are easier to absorb than a single big jump, and the habit matters more than the starting number.
One painless way to raise the rate is to split every raise. If your take-home pay rises by $200 a month, send $100 of it to savings the same month the raise starts and enjoy the other $100. Because you never got used to spending the full increase, it rarely feels like a sacrifice. Many workplace retirement plans offer an automatic escalation feature that raises your contribution by a set percentage each year, which applies the same idea without any effort on your part. Over a few years, these small steps can move a modest savings rate into a meaningful one.
Where the money should go first
Not all savings goals deserve equal priority. A common order looks like this. First, contribute enough to your workplace retirement plan to capture any employer match, since that is part of your compensation. Second, build a starter emergency fund, often one month of essential expenses, so a surprise bill does not land on a credit card.
Next, pay down high-interest debt such as credit card balances faster than the minimum. Paying off a card that charges a high interest rate offers a guaranteed return that is hard to beat with investments. After that, grow your emergency fund toward three to six months of essential expenses, depending on how stable your income is.
Once those foundations are in place, direct more toward long-term goals such as additional retirement savings in a 401(k) or IRA, a health savings account if you have an eligible high-deductible health plan, saving for a home down payment, or education savings. Short-term goals such as holidays, travel, and car replacement can have their own accounts, often called sinking funds, so those expenses do not disrupt your spending money when they arrive.
Setting it up so it runs automatically
Automation is what turns pay yourself first from an intention into a system. Start with what can happen through your employer. Retirement contributions to a 401(k) or 403(b) come out of your paycheck before you ever see the money. Many employers also let you split your direct deposit across multiple accounts, sending a fixed amount or percentage to a savings account at the same time as the rest goes to checking.
For savings outside work, schedule automatic transfers from checking to savings or investment accounts for the day your paycheck arrives, or the day after to allow for timing differences. Matching transfers to payday is important. A transfer scheduled for the end of the month can collide with rent and other bills, while one timed to payday moves money while the balance is at its highest.
Consider keeping savings at a different bank from your checking account. A little friction, such as a transfer that takes a day or two, makes it less tempting to dip into savings for impulse purchases. High-yield savings accounts at online banks can also earn more interest than a typical checking-linked account.
Some people go one step further and use two checking accounts: one for fixed bills and one for spending. On payday, savings come out first, the exact amount needed for bills goes to the bills account, and the remainder goes to the spending account. Whatever balance sits in the spending account is what you can spend, which makes it easy to know where you stand without tracking categories.
Handling irregular income
Pay yourself first works for freelancers, gig workers, commission earners, and others with uneven pay, but it needs adjustment. Fixed-dollar transfers can overdraw your account in a lean month. A percentage-based approach usually fits better. Each time a payment arrives, move a set percentage to savings, and set aside a separate percentage for taxes if no one is withholding them for you.
Another approach is to pay yourself a steady salary. Deposit all income into a holding account, then transfer the same amount to your personal checking account each month based on a conservative estimate of your income. Savings and tax money come out of the holding account first, and any surplus in good months builds a buffer for slow ones. Self-employed workers should also plan for estimated quarterly tax payments as part of their plan.
Common pitfalls and how to avoid them
The most common problem is setting the savings amount too high at the start. If you regularly transfer money back out of savings to cover bills, the system is signaling that the rate is unrealistic. Lower it, stabilize your cash flow, and increase it gradually. Moving money back and forth defeats the purpose and can lead to fees if your checking balance runs short.
Another pitfall is ignoring irregular expenses. Annual insurance premiums, car registration, holiday gifts, and medical bills are predictable over a year even if they are not monthly. If you do not plan for them, they will eat into your spending money or force you to raid savings. Sinking funds solve this by setting aside a small amount each month for each known irregular cost.
A third issue is lifestyle creep in the flexible spending pool. Pay yourself first frees you from tracking every dollar, but it does not make your fixed costs disappear. Keep an eye on recurring commitments such as subscriptions, car payments, and rent increases, which can quietly shrink the money left after savings and bills. A quick review every few months is usually enough.
How it compares with other budgeting methods
Pay yourself first is sometimes described as a reverse budget, because you plan savings first and let spending take care of itself. That contrasts with zero-based budgeting, which assigns every dollar a specific job and requires closer tracking, and with the 50/30/20 rule, which splits take-home pay into needs, wants, and savings.
These methods can work together. You could use the 50/30/20 framework to choose a savings rate of 20%, then implement it through automatic pay-yourself-first transfers. Or you could use a detailed budget for a few months to understand your spending, then switch to pay yourself first once you know your numbers. The best budget is the one you will keep using.
Is the pay-yourself-first budget right for you?
This method tends to work well for people with relatively steady income, predictable fixed costs, and a dislike of detailed tracking. It is also useful for anyone who saves consistently only when savings happen automatically.
It may need additional structure if you are struggling to cover essential bills, carrying significant high-interest debt, or frequently overspending without noticing. In those cases, a period of closer tracking can reveal where money is going before you switch to a lighter approach. Couples can use it too, by agreeing on a shared savings rate and then each keeping a personal spending allowance.
The bottom line
The pay-yourself-first budget puts savings at the front of the line. On payday, money goes automatically to your goals, your fixed bills are covered next, and what remains is yours to spend without tracking every dollar. Start with a savings rate you can sustain, prioritize the employer match, an emergency fund, and high-interest debt, then automate everything you can. Raise your rate over time, plan for irregular expenses, and review your setup every few months. Simple systems that run in the background are often the ones that last.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance Mastering delivers practical insights on personal finance, budgeting, investing, and money management. Whether you're just starting out or looking to grow your wealth, we make financial freedom achievable.










Comments (0)